CATCH THE WAVE

Myrtle Beach Real Estate

We Specialize in Myrtle Beach, SC Real Estate. Lots of options are waiting for you in Myrtle Beach, South Carolina and choosing the right realtors can help you in finding the perfect area and the right home for you and your family and make your dream a reality!  Let us help you in making one of the biggest, if not the biggest, decisions in your life.   

We were both born and raised along the Grand Strand and know the entire Horry County, so no matter what style of home you are looking for or what area you prefer, we can help you!  Please give us a call and let us help you make your dream a reality!  843-222-8566.

Eddie & Julie Boyd - The Boyd Team - Realtors

Myrtle Beach Real Estate - INNOVATE Real Estate


Aug. 27, 2026

Is Belle Harbor In Myrtle Beach, SC, The Right Neighborhood For You?

belle harbor myrtle beach

Belle Harbor is one of those neighborhoods that keeps coming up when people start seriously considering moving to Myrtle Beach, SC. It's got the amenities, the location, and the types of homes that work for a lot of different buyers.

But the "right" neighborhood looks different for every buyer. Some people need to be within walking distance of restaurants and shops. Others want peace and quiet above everything else. Your daily routine matters. Your housing preferences matter. What you actually do with your time matters more than what looks good in photos. Let's get into what it's actually like to live in Belle Harbor.

View More
Posted in Home Buying
Aug. 15, 2026

Everyday Mental Wellness: Fresh Ways to Support Your Emotional Health

Discover fresh, practical ways to support everyday mental wellness with personalized self-care, creative mood boosters, stress-reduction techniques, and healthy mini-habits. 


Busy parents juggling work and family, early-career professionals managing constant change, and caregivers carrying invisible worry often try the standard advice and still feel stuck. The core tension is simple: routines meant to support emotional health can start to feel stale, unrealistic, or mismatched to real life, making everyday mental wellness harder to sustain. Unique mental health practices and creative emotional support can offer a new way in, small shifts that feel more doable and more personal. With a grounded focus on mental health innovation, general readers' mental health can build momentum without pretending that deeper support isn’t sometimes needed.

Understanding Personalized, Safety-First Mental Care

Personalized mental care means pairing your nonnegotiables like sleep, movement, connection, and professional support when needed with a few add-on practices that match your stress style. It uses a holistic lens, noticing how your body, thoughts, relationships, and environment interact, while staying honest that no single tool works for everyone.

This matters because it is the most common health condition affecting 1 in every 5 individuals in the US, so “one-size-fits-all” advice often falls short. A safety-first approach helps you test unconventional strategies without chasing miracles, ignoring red flags, or dropping the basics.

Think of it like building a meal: a steady base plus small sides you can rotate. You try one new option at a time, track how you feel, and keep what actually helps. With that framework, you can sample breathwork, sensory grounding, guided relaxation, and a precise hemp-derived microdose option.

Try 4 Low-Risk Stress-Reduction Modalities You Can Test This Week

Once you know what feels safe and personally doable, it’s easier to experiment with a few gentle ways to calm your system. Four low-risk options to try: (1) breathwork, slow, steady breathing to dial down stress; (2) sensory grounding, using touch, sound, or sight to anchor yourself in the present; (3) ashwagandha, a commonly used adaptogenic herb; and (4) THCa, such as pure THCa isolate crystals, for a precise, customizable microdosing-style approach.

Pick 9 Uncommon Mood Boosters and Turn Them Into Mini-Habits

Treat mood support like a set of small experiments: pick one idea, keep it “low-risk,” and track how you feel before and after, just like you might with breathwork, grounding, or guided relaxation.

  1. Do a 7-minute “messy art” reset: Set a timer and make something intentionally imperfect, scribbles, torn-paper collage, or a single-color paint wash. The art therapy benefits come from externalizing feelings and giving your brain a nonverbal outlet, not from making something “good.” Pair it with one slow breath cycle: exhale as you make a mark, inhale as you step back.
  2. Try “tai chi between tasks” (3 minutes at a time): Learn one short flow (like weight shifting with slow arm circles) and do it between emails, after meetings, or before dinner. Tai chi mental wellness often shows up when movement is slow enough to notice your body and thoughts without wrestling them. If you already practice sensory grounding, add a simple cue: feel your feet pressing down as your shoulders drop.
  3. Build a birdwatching mindfulness micro-ritual: Step outside for 5 minutes at the same time daily and look for three bird behaviors, hopping, preening, calling, rather than species names. This gentle “attention training” can interrupt rumination because your mind has a job that’s interesting but not stressful. If you can’t get outdoors, try an open window and identify two distinct sounds.
  4. Test forest bathing effects with a “slow loop” walk: Walk a short route (10–20 minutes) and deliberately move slower than normal, pausing to notice texture, temperature, and light. Deeper shinrin-yoku practice can lower stress markers like cortisol, with a more in-depth practice of shinrin-yoku lowering blood pressure, heart rate, and cortisol. Make it easier by leaving your phone on airplane mode and choosing one sense to “lead” the walk.
  5. Volunteer in a tiny, repeatable way: Skip the all-day commitment and choose a weekly 15–30 minute action, writing one supportive note, packing one bag, making one check-in call, or picking up litter on one block. The volunteering psychological impact often comes from competence and connection: you did something real, and it mattered. Afterward, do a quick body scan and rate your stress 0–10 to see patterns.
  6. Use “pet proximity” even if you don’t own one: Pet ownership emotional health is often linked to routine and soothing touch, but you can create a version of that without adopting. Offer to walk a neighbor’s dog once a week, schedule a cat-sitting swap, or spend 10 minutes calmly brushing your pet while doing paced breathing. If animals aren’t accessible, mimic the rhythm with a warm mug in both hands and slow stroking on your forearm.
  7. Design a “kind boundaries” script and practice it aloud: Write one sentence you can reuse: “I can’t do that today, but I can do X,” or “I need 24 hours to decide.” Rehearsing it for 60 seconds builds nervous-system safety because your brain learns you have options, especially helpful if you’re already using relaxation recordings or breathwork. Try it first on low-stakes moments like rescheduling a call.
  8. Create a two-song mood bridge: Pick one song that matches your current mood and one that matches where you want to land (calmer, energized, steadier). Listen in order while doing a simple grounding task, washing dishes, stretching, or organizing one drawer, so your body links sound with regulation. Keep it short and repeatable: the goal is a reliable “switch,” not a perfect playlist.
  9. Make a 3-line “evidence log” after any experiment: Write: “What I did,” “What I noticed,” “What I’ll tweak next time.” This keeps your experiments honest and helps you compare what works across modalities, movement, nature, service, creativity, and calming routines. Over a couple weeks, you’ll have clear clues about which mini-habits fit you best.


Everyday Mental Wellness Q&A, Made Simple

Q: What’s a “safe” mental wellness experiment to start with?
A: Choose something low-intensity, time-limited, and easy to stop, like 3 to 7 minutes of gentle movement or a short sensory reset. Avoid anything that involves pain, breath-holding, extreme temperature, or pushing through dizziness. If you’re unsure, use a simple rule: you should feel more grounded, not more pressured.

Q: How soon should I expect these ideas to change my mood?
A: Many practices offer small, same-day shifts in tension or focus, not instant happiness. Treat improvement as trend data: look for slightly easier mornings, quicker recovery after stress, or fewer spirals over 2 to 3 weeks. Track one rating before and after to keep expectations realistic.

Q: How do I personalize a plan without getting overwhelmed?
A: Pick one goal, one practice, and one time of day, then repeat it for a week before adding anything new. Your plan is allowed to be basic, especially since 1 in 5 US adults live with a mental health condition.

Q: Can these tools replace therapy or medication?
A: They can support your daily stability, but they are not a substitute for clinical care when symptoms are significant or persistent. Use them as “between-session” skills or lifestyle scaffolding, and keep your care team informed if you have one.

Q: When should I seek professional help right away?
A: Reach out urgently if you have thoughts of harming yourself, feel unsafe, can’t perform basic daily tasks, or notice rapid mood changes, panic that won’t settle, or substance use increasing. If distress lasts more than two weeks or keeps returning, it is a strong sign to talk with a licensed professional.

Small Daily Choices That Strengthen Everyday Mental Wellness

When stress stacks up, it’s easy to feel like emotional health requires fixing everything at once, or not starting at all. A steadier path comes from treating this as an empowering mental health journey built on realistic expectations, gentle self-compassion techniques, and continued mental wellbeing support when needed. Over time, motivational wellness actions create positive lifestyle changes that make mood shifts easier to notice, name, and navigate. Progress is choosing the next kind step, not forcing a perfect plan.


Posted in BoydTeam Blog
Aug. 6, 2026

Balancing Family Ties and Independence When You Relocate Nearby

Learn how to move closer to family while maintaining your independence, setting healthy boundaries, protecting your career, and creating lasting balance.

For mid-career adults considering moving closer to relatives, family relocation challenges rarely start with logistics and often start with identity. The core tension is clear: the pull of family closeness vs autonomy, especially when love, obligation, and old roles resurface at the same time. Maintaining independence can feel harder when support is expected, privacy gets thinner, and decisions start to attract opinions. With the right lens, personal autonomy doesn’t have to be the price of proximity.

Understanding Relocation Tradeoffs Near Family

Moving closer to family works best when you treat it as a values-related decision, not a rescue mission. The core idea is to relocate with a clear plan for boundary setting, personal autonomy, and career identity, so your choices come from intention instead of guilt. Healthy limits matter because boundary setting is an essential part of self care, and it protects relationships from turning into silent contracts.

This matters because proximity can quietly expand expectations, from weekly dinners to on-call help. When you define what you can offer, you keep your time, money, and energy aligned with your life stage. You also protect career momentum, since many people relocate for better job security when stability is on the line.

Picture choosing a home base near relatives while keeping “office hours” for family support. You can be available and still say no to drop-ins, last-minute errands, or career compromises. Independence stays intact because the rules are clear before the move. With tradeoffs clear, career-pivot barriers and work-life strategies become easier to choose.

Use a Family-Centered Move to Plan a Smart Career Pivot

Once you’ve weighed the tradeoffs of living closer to family, the move itself can also become a meaningful reset for your work life. Changing careers during (or right after) a relocation can be a fresh start that brings your professional goals into better alignment with your personal priorities, especially if you intentionally pursue roles that protect flexibility, support growth, and reinforce your independence. That matters in a moment when burnout and dissatisfaction are rising, and studies suggest many employers are leaning more on external hiring rather than developing the talent they already have, widening skills gaps and limiting advancement for both workers and organizations. If you’re trying to pivot while managing family responsibilities, research-informed support can help you see realistic options and understand the barriers many adult workers face; a concrete place to explore is career help at University of Phoenix.

Follow This Move Plan for Space, Time, and Work

A move closer to family works best when you treat it like a transition with guardrails, not a permanent open-door policy. Use this 10-point plan to choose the right location, set expectations early, and protect the work rhythm that supports your independence.

  1. Pick your “independence radius” first: Decide how close is close enough before you look at listings: many people do well at 15–30 minutes away, nearby for dinner, far enough to avoid constant drop-ins. Write down your ideal visit frequency (e.g., weekly dinner) and non-negotiables (quiet mornings, gym time, kid routines). This keeps the move aligned with the career-pivot priorities you set earlier, like predictable focus time and commute limits.
  2. Use neighborhood selection criteria that match real life, not fantasy: Make a simple scorecard with 6–8 criteria: commute to your work hub, access to groceries/pharmacy, noise level, parking/transit, walkability, proximity to your friends/activities, and distance to family. Tour the area at two different times (one weekday evening, one weekend morning) and note traffic, lighting, and how you feel being there. Choose the neighborhood that supports your routines, even if it’s not the closest.
  3. Set a “transition timeline” with checkpoints: Break the first 90 days into phases, Week 1: essentials and recovery; Weeks 2–4: work rhythm; Weeks 5–8: family rhythm; Weeks 9–12: adjust. Put two 20-minute check-ins on the calendar (end of Week 2 and end of Month 2) to ask: “What’s working? What’s draining? What needs a boundary?” This is everyday-life transition planning, similar to how embedding transition planning into routine processes prevents avoidable value loss.
  4. Use two boundary scripts, one for time, one for access: Practice saying, “We’d love to do Sundays twice a month, want to pick the first and third?” and “Text before coming by; if I don’t confirm, assume it’s not a good time.” Clear language reduces resentment because it removes guesswork. If you feel awkward, remember you’re not rejecting people, you’re protecting the conditions that let you show up well.
  5. Create a default visit rhythm that doesn’t rely on willpower: Choose one recurring anchor (weekly dinner, monthly brunch, school pickup every other Friday) and one flexible slot (a rotating weekend afternoon). Anchors build closeness; the flexible slot keeps your calendar from becoming an automatic “yes.” Share the rhythm early so help requests can land in the right place.
  6. Build your work routine adjustments into the move, not after: Pick your “protected hours” for deep work and communicate them to family the same way you would to coworkers. Set a start/stop ritual (walk, coffee on the porch, quick plan for tomorrow) so work doesn’t bleed into family time. If you’re pivoting roles, treat your schedule like a transition strategy, your personal version of a business transition strategy, so work remains stable while everything else changes.
  7. Decide in advance what help you can offer, and what you can’t: Make a short “yes list” (rides to appointments with 72-hour notice, one weekly errand run) and a “not now list” (same-day emergencies except true crises, ongoing tech support). When requests come, you can respond calmly: “I can do Tuesday after 5, or I can help you find another option.” Having a plan makes guilt less persuasive and boundaries easier to keep.

Questions People Ask Before Moving Near Family

Q: How close is “close enough” without feeling smothered?
A: Choose a distance that supports your routines, not just their convenience. Many people feel best when they can show up easily but still have a natural buffer for unplanned drop-ins. Pick a travel time you can sustain on a work night, then commit to it.

Q: What if my family expects me to be available all the time?
A: Name expectations early and keep them simple: how often you visit, how you handle last-minute requests, and what needs a heads-up. Use consistent language like, “I can do X day, not today,” so the pattern becomes normal. Boundaries feel kinder when they are predictable.

Q: How do I deal with guilt when I say no?
A: Treat guilt as a signal, not a rule. Offer a clear alternative you can actually keep, such as one weekly check-in call or a planned errand day, and let that be your “yes.” You are building reliability, not rejecting anyone.

Q: Can I protect my career while relocating closer to family?
A: Yes, if you plan work stability like a priority, not an afterthought. Career growth is a common reason people move, with career advancement topping many relocation motivations, so it is reasonable to safeguard your schedule and opportunities. Tell the family your work blocks in advance and keep them as firm as any meeting.

Q: What’s a good way to stay connected without overcommitting?
A: Pick one repeating touchpoint you enjoy and one optional slot you can decline when life is full. That could be a standing dinner plus a flexible weekend visit. Consistency builds closeness more than constant availability.

Move Near Family While Keeping Career Momentum and Independence

Moving closer to family can feel like trading freedom for obligation, especially when boundaries, guilt, and career growth are all on the line. The steadier path is a values-led move: define what closeness looks like, communicate limits early, and keep long-term independence strategies at the center of daily decisions. With that mindset, the reflective transition benefits show up fast, more support and connection, with less resentment and more choice, creating real empowerment moving closer. Closeness works best when it’s chosen, bounded, and built to last. In the next seven days, choose one conversation to have or one boundary to restate in plain language. That small step helps balance family and career growth while embracing change positively, building resilience that holds through the next season.

Posted in BoydTeam Blog
July 28, 2026

How to Manage Debt Before Buying a Home and Get Mortgage Ready

For prospective homebuyers aiming to buy within the next 6–12 months, debt management challenges often become the hidden obstacle that derails a confident timeline. The impact of debt on mortgage approval can show up as higher required payments, stricter lender scrutiny, or an approval that arrives smaller than expected. Credit score importance matters here because it signals how reliably balances have been handled over time, and it can shape the terms a lender is willing to offer. Real financial readiness for a home purchase means knowing which debts are weighing down the application so energy goes to the few factors that matter most.

Use These 7 Debt Moves to Strengthen Your Mortgage Profile

When you’re 6–12 months from buying, debt management is less about “being perfect” and more about improving the numbers lenders watch: your monthly obligations, credit utilization, and payment history. Use these moves like a training plan: small, consistent reps that build a stronger mortgage profile.

  1. Run a credit “checkup” and fix errors fast: Pull your credit reports, scan for incorrect late payments, wrong balances, or accounts that aren’t yours, then dispute anything inaccurate. Cleaning up errors can boost your score and reduce underwriting questions. Also set up autopay for at least the minimums so payment history stays spotless while you focus on payoff.

  2. Set a debt-cutting budget that targets your debt-to-income ratio: Track the last 30 days of spending, then assign every dollar a job: essentials, minimum payments, and a specific “extra payment” amount. The habit of setting and maintaining a budget helps you manage debts and expenses consistently, which is exactly what lenders want to see. Start with a realistic weekly “debt sprint” number, even $50–$100 extra, so you can repeat it without burning out.

  3. Lower credit utilization before you pay off everything: For mortgage readiness, utilization can move the needle quickly. Aim to keep each card under 30% of its limit, and if you can, under 10% for your strongest score impact. Make an extra mid-cycle payment (not just on the due date) to reduce the balance that gets reported to the bureaus.

  4. Prioritize high-interest balances, then lock in the win: List debts by APR and attack the highest rate first while paying minimums on the rest (avalanche method). This frees cash flow faster, which supports the “monthly payment” side of approval. Example: if you have two cards, send every extra dollar to the 24% APR card until it’s gone, then roll that payment to the next balance.

  5. Consider consolidation only if it improves the math (and the behavior): Consolidation can help if it lowers your interest rate, simplifies payments, and doesn’t extend debt forever. Right now credit card interest rates are around 24% on average, so a lower-rate consolidation loan or balance transfer may reduce how much interest you’re feeding each month. Before you apply, calculate the new payment, fees, and payoff timeline, and commit to not re-running balances back up.

  6. Boost income with a “lender-friendly” plan: Choose income that’s stable and documentable: extra shifts, a part-time W-2 role, or consistent freelance work with clean invoices and deposits. Use a simple rule: 50% of the extra income goes to targeted debt payoff, 50% builds a small cash cushion so you don’t rely on credit for surprises. More income plus lower payments often improves the ratios lenders use.

  7. Use professional debt counseling when you need structure: If you’re juggling multiple accounts, high minimums, or missed payments, a nonprofit credit counselor can help you map a payoff plan or evaluate a debt management program. Ask for a written breakdown of fees, timelines, and how accounts will be handled so there are no surprises during underwriting. The goal is clarity, consistency, and a paper trail you can explain confidently.

Build a One-Folder Document System Lenders Can Read Fast

Once you’ve tightened up your debt moves, the next advantage is being able to prove your progress quickly when a lender asks. Keep your financial records organized, current, and easy to grab, so when pre-approval or underwriting requests an update, you’re not hunting through emails, screenshots, or scattered files. If you need to share anything with your lender (or anyone else involved), PDFs are often the preferred format because they’re consistent and easy to open. When you need a quick standard file, an online option to convert PDF files free of charge can make it as simple as dragging and dropping the document and saving the clean PDF. With your paperwork ready to send on demand, you can build a month-by-month payoff timeline that stays realistic as new requests roll in.

Plan → Pay → Track → Check In

Your paperwork is ready, so now you need a rhythm you can repeat without burnout. This workflow turns “get mortgage ready” into simple monthly milestones that steadily reduce balances, strengthen credit habits, and keep you prepared for lender follow-ups.


Stage

Action

Goal

Map the runway

Pick a 6 to 12 month date; list debts, rates, and minimums

One clear timeline and starting baseline

Choose a payoff path

Use Snowball Method or prioritize highest interest first

A strategy you can follow consistently

Automate the minimums

Set autopay for every minimum; schedule extra payment day

No missed payments and steady momentum

Target one “focus debt”

Send all extra money to one balance until cleared

Visible wins and fewer monthly obligations

Track credit signals

Review statements and score trends; dispute obvious errors

Better readiness since 35% of your credit score comes from payment history

Run a lender-style check

Update DTI estimate; confirm cash reserves and documentation

Confidence to start pre-approval conversations


Each stage feeds the next: your map guides the payoff path, automation protects consistency, and a single focus debt keeps the plan measurable. The monthly check ties progress to lender expectations, so you adjust early instead of scrambling later.

Mortgage-Ready Debt FAQs Homebuyers Ask

Q: What is a debt-to-income ratio, and why do lenders care so much?
A: Debt-to-income ratio compares your monthly debt payments to your gross monthly income. Lenders use it to judge whether your budget can handle a mortgage payment plus your current obligations. A practical next step is to total your minimum monthly debt payments and divide by gross income so you can see where you stand.

Q: How do student loans affect mortgage approval if my payment is low or paused?
A: Even with a pause or very low payment, lenders often count a payment amount to avoid “surprise” future obligations. Bring your loan statement and repayment plan details so the lender can use the most accurate figure. If you can, enroll in a documented payment plan before applying.

Q: Which debts hurt the most, and what should I pay down first?
A: Revolving credit card balances often hit hardest because they raise utilization and increase monthly minimums. Paying a card down below a key utilization threshold can improve both your DTI and credit profile. Focus on extra payments where you’ll reduce the required monthly payment fastest.

Q: Can I close credit cards to boost my credit score before a mortgage?
A: Closing cards can reduce available credit and potentially raise utilization, which may lower your score. A safer move is to keep older accounts open, pay balances down, and avoid new charges. If an annual fee is hurting your budget, ask about a product change instead.

Q: What should I say when a lender asks about deposits, transfers, or “new debt”?
A: Keep it simple, factual, and documented: where the money came from, when it moved, and why. Save screenshots or statements for any large deposits and be ready to explain them in one or two sentences. If you’re unsure what counts as “large,” ask your loan officer how they define it and follow that rule consistently.

Build Mortgage Confidence by Managing Debt with Clear Next Steps


Debt can feel like the one thing standing between a solid down payment plan and a lender’s “yes,” especially when questions about ratios and credit get personal. The steady way through is empowered financial decision-making, embracing personal finance control with calm, consistent choices that build confidence in debt management and support long-term homeownership planning. Apply that mindset and the numbers start telling a clearer story: lower stress, cleaner documentation, and a stronger mortgage-ready profile. Control the debt, and the mortgage process gets simpler.


July 15, 2026

Emmens Preserve, Myrtle Beach: Your Complete Neighborhood Guide

emmens preserve myrtle beach

If you’re exploring Emmens Preserve, Myrtle Beach, as part of your home search, you’re likely drawn to something more than just a house. You want a neighborhood that feels connected, thoughtfully designed, and easy to enjoy day-to-day. 

Tucked within the popular Market Common district, Emmens Preserve offers a unique blend of green space, coastal charm, and modern living that continues to attract buyers looking at living in Myrtle Beach, SC. 

Let’s break down what makes this neighborhood stand out and discover whether it’s the right fit for you. 

Emmens Preserve is located within The Market Common in the southern section of Myrtle Beach, just a short distance inland from the Atlantic coastline. This puts it in a sweet spot geographically: close enough to the beach for easy access, while still offering a more residential, thoughtfully planned setting away from the busiest tourist areas.

View More
Posted in Home Buying
July 7, 2026

How to Turn Your Favorite Family Beach Vacation into a Smart Investment Property

Introduction

There is a certain kind of magic that happens every summer when your family pulls into the same beach town, unpacks the same faded beach bags, and walks the same stretch of sand you have visited for years. Maybe it is a cottage in the Outer Banks, a condo in Destin, or a weathered bungalow on the Jersey Shore. Whatever the location, that place holds memories, and for many families, it also holds an opportunity that is easy to overlook.

What if that beach house you rent every July could actually belong to you? What if the money you spend year after year on vacation rentals could instead build equity, generate income, and eventually pay for itself? Turning a beloved vacation spot into an investment property is not just a dream reserved for the wealthy. With the right research, financing strategy, and management plan, many families are discovering that owning a piece of their favorite coastline is more attainable than they think.

This article walks through the practical steps of transforming sentimental attachment into a sound financial decision. We will cover how to evaluate the market, how to finance the purchase, how to manage the property once you own it, and how to protect your investment for the long haul. By the end, you should have a clear framework for deciding whether your family's favorite beach getaway could become your next smart investment.

Section 1: Evaluating the Market Before You Fall in Love with a Location

Emotional attachment is a wonderful reason to want a property, but it should never be the only reason you buy one. Before you start browsing listings in your favorite beach town, take a step back and evaluate the market with a clear head.

Start by researching the local real estate trends over the past five to ten years. Has property appreciation kept pace with, or outpaced, the national average? Coastal markets can be volatile, and some towns experience much stronger long-term growth than others. Websites that track regional housing data, along with local real estate agents who specialize in vacation properties, can give you a realistic picture of where the market has been and where it might be heading.

Next, look closely at rental demand. Even if you plan to use the property primarily for your own family, renting it out during weeks you are not there can significantly offset your costs. Check occupancy rates for similar properties in the area, average nightly rates during peak and off-peak seasons, and how quickly comparable homes get booked. Local property management companies are often happy to share this kind of data with prospective buyers, since it helps them attract future clients too.

Consider the seasonality of the location as well. Some beach towns are booming ten to twelve months a year, drawing retirees, remote workers, and off-season travelers. Others are essentially ghost towns outside of summer. A property in a year-round destination will typically generate more consistent income and appreciate more steadily than one in a strictly seasonal market.

Finally, pay attention to local regulations. Many coastal towns have introduced strict short-term rental ordinances in recent years, including caps on the number of rental permits issued, minimum stay requirements, and even outright bans in certain zones. Before falling in love with a specific street or building, confirm that short-term rentals are actually legal there, and check whether the rules are likely to become more restrictive in the future. A property that looks perfect on paper can quickly become a poor investment if local law prevents you from renting it the way you planned.

Section 2: Financing the Purchase Without Overextending Your Family

Once you have identified a market that makes financial sense, the next challenge is figuring out how to pay for it. Financing a vacation property is different from financing a primary residence, and it pays to understand those differences before you start shopping for a mortgage.

Lenders typically classify these purchases in one of two ways: as a second home or as an investment property. A second home is one you intend to occupy yourself for a portion of the year, while an investment property is one purchased primarily to generate rental income. The distinction matters because investment property loans usually come with higher interest rates, larger down payment requirements, and stricter credit criteria. If you plan to use the home yourself part of the year and rent it out the rest of the time, be upfront with your lender about your intentions, since misrepresenting the property type can create serious problems down the road.

Down payments for second homes generally start around ten percent, while investment properties often require twenty to twenty five percent or more. Building up that reserve ahead of time, rather than scrambling at the last minute, gives you far more negotiating power and a wider range of loan options.

It is also worth exploring whether a home equity line of credit on your primary residence could help fund the down payment, or whether a cash-out refinance makes sense given current interest rates. Some families choose to partner with siblings or close friends to split the purchase price and future usage, which can lower the individual financial burden significantly, though this route requires a clear written agreement covering usage schedules, maintenance responsibilities, and an exit strategy if one party wants to sell their share later.

Do not forget to budget beyond the mortgage itself. Property taxes in coastal areas can be higher than inland comparables, homeowners insurance often includes separate flood and windstorm coverage that adds substantially to the annual cost, and homeowners association fees in condo buildings or gated communities can be significant. Run a full cost analysis, including furnishing the property, before committing to a purchase price, so there are no surprises once you are the one holding the keys instead of the one making the reservation.

Section 3: Managing the Property for Income and Longevity

Owning a beach property is only half the equation. Managing it well is what determines whether it becomes a source of steady income or a source of constant headaches.

The first major decision is whether to self-manage or hire a professional property management company. Self-managing gives you more control and saves on management fees, which typically range from twenty to thirty percent of rental income, but it also means you are responsible for guest communication, cleaning coordination, maintenance emergencies, and marketing the listing, often from hundreds of miles away. A professional management company handles all of this for you, and many also offer dynamic pricing tools that adjust nightly rates based on demand, which can meaningfully increase your annual revenue compared to a flat rate you set yourself.

Whichever route you choose, building a reliable team of local service providers is essential. A trustworthy cleaning crew that can turn the property around quickly between guests, a handyman who can respond to minor repairs without delay, and a landscaper familiar with coastal plants and salt air exposure will all save you time and stress. It is also smart to schedule regular maintenance for systems that take a beating in a beach environment. Salt air and humidity are especially hard on HVAC systems, so bringing in professional air duct cleaners on a routine schedule helps prevent mold buildup, improves air quality for guests, and extends the life of your equipment considerably. Skipping this kind of preventive maintenance often leads to far more expensive repairs later.

Marketing your property effectively also matters. High quality photography, an accurate and detailed listing description, and active management of guest reviews can make a real difference in booking rates. Many owners find success listing on multiple platforms simultaneously, while others prefer to build a direct booking website to avoid platform fees altogether once they have an established base of repeat guests.

Finally, think carefully about how you will balance personal use with rental income. If your family wants the same two weeks every summer, block those dates well in advance and build your rental calendar around them. Being upfront about your own usage needs from the start prevents scheduling conflicts and helps you set realistic income expectations.
Section 4: Protecting Your Investment for the Long Term

A smart investment property is one that holds its value and continues generating returns for years, not just one that looks good on the first year's spreadsheet. Protecting that long-term value requires a bit of foresight.

Insurance is the first line of defense. Standard homeowners insurance typically does not cover flood damage, and coastal properties are, by definition, at higher risk. Separate flood insurance, and in some regions, windstorm or hurricane coverage, is essential. Review your policy annually, since coverage needs can change as property values rise and as local flood zone maps are updated.

Building a reserve fund specifically for the property is another smart move. Beach properties face wear and tear that inland homes simply do not, from salt corrosion on exterior fixtures to more frequent repainting needs. Setting aside a percentage of your rental income each month, rather than spending every dollar of profit, ensures you are prepared for a new roof, a replaced water heater, or storm damage repairs without having to take on emergency debt.

Stay engaged with the local community and local government as well. Zoning laws and short-term rental regulations can shift, sometimes quickly, in response to community pressure or new local leadership. Attending town meetings, joining local homeowner associations, or simply staying in touch with a knowledgeable local agent can help you anticipate changes before they affect your bottom line.

Lastly, revisit your investment goals periodically. Markets shift, family needs change, and what made sense five years ago might not make sense today. Some owners eventually choose to sell and reinvest in a different location as their family's travel patterns evolve, while others hold on for decades and eventually pass the property down as a multi-generational asset. Either path can be the right one, as long as it is a deliberate choice rather than something that happens by default.

Conclusion

Turning your family's favorite beach vacation into a smart investment property is a journey that blends heart and strategy in equal measure. It starts with genuine research into the local market, continues through a financing plan that fits your family's real budget, depends on thoughtful property management once you own it, and requires ongoing attention to protect the investment for years to come. Done thoughtfully, it is entirely possible to turn those cherished summer memories into a property that pays you back, both financially and emotionally, for generations.


If you have a beach town that already feels like home, now is the time to start exploring what ownership could look like. Talk to a local real estate agent who understands vacation rental markets, get pre-qualified with a lender who specializes in second home or investment property loans, and start building the team of local professionals who will help you manage the property well. Your family's favorite stretch of sand might be closer to becoming your own than you ever imagined.

Posted in BoydTeam Blog
June 28, 2026

How to Use Your Home Equity to Buy Your First Rental Property Safely

Homeowners with steady income and a growing cushion of equity often see a clear investment property opportunity: using home equity to fund first rental property financing without waiting years to save a full down payment. The core tension is real, leveraging a primary residence can accelerate wealth-building, but it can also raise the stakes if payments tighten, vacancies hit, or costs run higher than expected. Many first-time landlords get stuck between excitement and fear because the risks of leveraging home equity feel personal when the collateral is home. With a clear-eyed approach, homeowners can weigh opportunity against downside and move forward with confidence.

Understanding Home Equity Financing Basics

First, get clear on the three main ways to tap your equity. A home equity loan gives you a one-time lump sum, while a HELOC works more like a reusable credit line you draw from as needed. Cash-out refinancing replaces your current mortgage with a bigger one and pays you the difference in cash.

To estimate what you can access, start with your home’s current value minus what you owe, then factor in a lender’s maximum borrowing limit. Lenders also look at credit, income, cash reserves, and your total monthly debt compared to income, especially when the new purchase is a rental.

Think of equity like stored savings in your walls. If your home is worth $450,000 and you owe $300,000, the gap is your starting point, then the bank sets the usable portion. With these basics clear, gathering the right paperwork becomes simpler and faster.

Build a “Lender-Ready” Document Pack and Keep It Locked Down

Once you understand how home equity loans, HELOCs, and cash-out refis work, the next win is making the paperwork side move just as smoothly. Keeping your mortgage statements, recent property valuations, and any existing loan documents organized in one place makes it easier to compare options and spot what you can realistically afford before you commit your home equity. Add your rental income projections (even simple ones) alongside any lender requirements you’re given, and you’ll be able to answer questions quickly without digging through email threads or piles of paperwork, reducing underwriting back-and-forth.

When you save everything as PDFs, you create a consistent, easy-to-open format that preserves the original details and layout, so what you send is exactly what the lender sees. Because these files can include account numbers and other sensitive information, consider using a tool to encrypt a PDF file so only someone with the correct password can access your documents. With your document pack ready and secured, you’ll be in a stronger position to follow the next section’s 7-stage plan before you tap your equity.

Plan → Validate → Finance → Stress-Test → Commit

This rhythm transforms “should we use home equity?” into a calm, repeatable decision cycle. It helps you size your borrowing, test the deal against real-world rent swings, and keep your household budget protected before you sign.


Stage

Action

Goal

Map equity

Estimate usable equity and set a max monthly payment

Clear borrowing ceiling you can live with

Scan rents

Review comps, vacancy signals, and rent trend notes

Conservative income target, not best-case

Price financing

Compare HELOC, loan, and refi terms; list fees

True cost of capital, all-in

Build a buffer

Draft a budget with reserves and repair allowance

Cushion for surprises and cash flow gaps

Pre-qualify

Provide personal financial information and clarify lender rules

Fewer approval surprises and cleaner timelines

Stress-test

Re-run numbers with lower rent; CMHC notes average turnover rent for 2-bedroom units fell in most major centres

A deal that still works under pressure


Each stage tightens the next: your equity cap guides property targets, financing costs shape your budget, and the stress-test validates the whole plan. When something fails, loop back and adjust assumptions instead of forcing the purchase.

Home-Equity Rental Property Questions, Answered

Q: What do lenders usually look at when I borrow against my home?
A: They want proof you can handle the payment even if rent is bumpy. Expect income, credit, existing debts, and your equity to matter, plus clear documentation like a profit and loss, balance sheet, or cash flow statement if you have self-employment or side income. Ask what debt-to-income target they use before you shop seriously.

Q: How much of my home equity should I actually use?
A: Set a ceiling based on a payment you can cover from your household income alone. If the deal only works when the property performs perfectly, it is too tight. Keep room for repairs, taxes, and rate changes.

Q: What are the biggest risks of a HELOC or home equity loan?
A: You are putting your primary home on the line, so a bad stretch can affect more than your investment. Variable rates can rise, and minimum payments can jump. Get the full fee list, understand the draw and repayment periods, and build a plan to pay it down faster when cash flow is strong.

Q: Why do I need a cushion if the rent should cover the mortgage?
A: Vacancies and turnover are normal, and the downtime can be longer than people expect. In one market snapshot, void periods averaged 23 days, which can erase a month of profit fast. A reserve fund helps you stay calm and avoid using credit cards when the unit is empty.

Q: How do I stress-test a rental deal before I commit?
A: Run the numbers with lower rent, higher repairs, and at least one full month of vacancy. Add a “boring” line item for maintenance and a separate line for big-ticket replacements. If you still have breathing room, you are buying safety, not just potential.

Building a Cash Cushion for Safer Home-Equity Rental Investing


Using home equity to buy your first rental can feel like a tug-of-war between opportunity and overextending your household finances. The safest path is the mindset this guide emphasized: financial preparedness first, paired with responsible landlord practices and a deliberate plan for building an investment cushion before risk grows. When that foundation is in place, the property becomes a business you can manage calmly, protecting your primary home while setting up long-term rental success and empowering first-time landlords to stay in the game. A rental is only a good deal if your cushion can carry the surprises.


Posted in BoydTeam Blog
June 24, 2026

The Ultimate Travel Guide to Myrtle Beach for Future Property Buyers

Introduction: Why Myrtle Beach Deserves a Spot on Your Investment Radar

There are beach towns, and then there is Myrtle Beach. Stretching along 60 miles of South Carolina's Atlantic coastline, this vibrant coastal city has long captured the hearts of vacationers, retirees, and savvy real estate investors alike. With its golden sandy shores, warm subtropical climate, and a cost of living that remains far more accessible than comparable beach markets, Myrtle Beach occupies a unique sweet spot in the American property landscape.

But buying a home or investment property anywhere requires more than browsing listings online. You need to feel the rhythm of a place, understand its neighborhoods, experience its seasons, and envision your life within its geography. That is exactly what a well-planned visit to Myrtle Beach can give you. Whether you are drawn by the idea of a vacation rental generating passive income, a retirement retreat, or a permanent coastal relocation, this travel guide will walk you through everything you need to see, explore, and evaluate before you sign on the dotted line.

Section 1: Getting to Know the Landscape, Neighborhoods, and Lifestyle

Myrtle Beach is not a single destination; it is a collection of distinct communities, each with its own personality, price point, and appeal. Understanding these neighborhoods during your visit is perhaps the most important groundwork you can lay as a prospective buyer.

The heart of it all is the Grand Strand, a 60-mile stretch of coastline that runs from Little River in the north down to Pawleys Island in the south. Within this corridor, areas like North Myrtle Beach tend to attract families and long-term residents looking for a quieter, more residential feel. The downtown Myrtle Beach area, centered around the iconic boardwalk, buzzes with tourist activity year-round and is prime territory for short-term rental investors targeting visitors who want to be in the thick of things.

Further south, communities like Surfside Beach and Murrells Inlet carry a more laid-back, small-town character. Murrells Inlet, in particular, has earned its title as the "Seafood Capital of South Carolina," and its marshwalk lined with waterfront restaurants and marinas makes it one of the most charming areas to spend an evening. Buyers interested in a slower pace of life without sacrificing coastal access tend to fall hard for this stretch of the Grand Strand.

During your visit, rent a car and simply drive. Take Ocean Boulevard from one end of the strip to the other. Wind through the residential streets of Carolina Forest, one of the fastest-growing master-planned communities in the state, where large family homes sit alongside top-rated schools and retail conveniences. Spend a morning at Barefoot Landing in North Myrtle Beach and an afternoon exploring the quiet inlets of Pawleys Island. These firsthand impressions will shape your investment decisions far more powerfully than any online search filter ever could.

Section 2: What to Do, See, and Experience as a Visitor (and Future Resident)

A visit to Myrtle Beach should be part vacation, part scouting mission. The good news is that both objectives align beautifully because the experiences that make this destination attractive to tourists are largely the same ones that make it desirable for long-term living.

Start with the beaches themselves. The wide, gently sloping shores are ideal for swimming, surfing, shelling, and early morning walks. During peak season, Myrtle Beach State Park offers a more natural, uncrowded alternative to the bustling main beach, and its proximity to nature trails and the Atlantic Ocean makes it a beloved feature for residents who crave outdoor space.

Golf is a defining pillar of the Myrtle Beach lifestyle. With over 80 championship courses woven throughout the Grand Strand, this region rivals any golf destination in the country. For potential buyers who love the sport, a property here is not just a home; it is a lifestyle upgrade. Many residential communities are built around these courses, offering stunning views and easy tee-time access.

The entertainment and dining scene has evolved considerably over the past decade. Broadway at the Beach remains a top draw for tourists, featuring restaurants, live entertainment, and the largest concentration of retail in the region. However, the local food scene extends well beyond the tourist zones. Local oyster bars in Murrells Inlet, fresh seafood shacks along Highway 17, and an increasingly diverse range of restaurants reflect the growing permanent population and its sophisticated tastes.

For those comparing coastal destinations before making a decision, consider that even iconic experiences like tours new zealand offer are rooted in the same principle that makes Myrtle Beach compelling: the best destinations reward those who take the time to explore them on foot, by car, and through genuine local experiences, not just a highlights reel.

Section 3: The Real Estate Market, What Buyers Need to Know

No property buying guide would be complete without a frank look at the market dynamics. Myrtle Beach has been one of the most consistently performing real estate markets in the southeastern United States, driven by a steady influx of retirees from the Northeast and Midwest, strong short-term rental demand, and relatively affordable entry prices compared to Florida's coastline.

As of the mid-2020s, the median home price in the Myrtle Beach area remains significantly below the national average for coastal markets. This affordability factor, combined with South Carolina's relatively low property taxes and the absence of a state income tax on retirement income, creates a compelling financial case for buyers considering this market seriously.

The short-term rental market is particularly robust. Platforms like Airbnb and VRBO see strong year-round booking activity in Myrtle Beach, though peak season runs from Memorial Day through Labor Day. Buyers targeting investment properties should research HOA regulations carefully, as some communities restrict short-term rentals while others are specifically designed to accommodate them.

During your visit, take time to walk through open houses in different price brackets. Talk to local real estate agents who specialize in the area; their knowledge of upcoming developments, flood zones, and neighborhood trajectory is invaluable. Pay attention to which communities are growing, where new infrastructure investments are being made, and how close properties are to both beach access and everyday conveniences like grocery stores, healthcare facilities, and major roads.

One consideration that many first-time coastal buyers underestimate is insurance. Properties near the water in South Carolina require wind and flood insurance in addition to standard homeowner's coverage. Factor these ongoing costs into your budget early in the process, and ask local agents to walk you through realistic annual insurance estimates for properties you are seriously considering.

Section 4: Practical Tips for Planning Your Property-Buying Trip

Visiting Myrtle Beach with the specific intention of evaluating it as a place to buy requires a slightly different approach than a standard leisure trip. Here is how to make the most of your time on the ground.

Plan your visit during shoulder season, typically March to May or September to October. During these months, the crowds thin out, rental prices drop, and you get a much more honest picture of what everyday life looks like in the community. It is easy to fall in love with any beach town during the height of summer; the real test is how a destination feels when the tourist tide recedes.

Schedule at least three to four full days, ideally a week. Use the first couple of days to explore different neighborhoods without any pressure. Eat at local spots that are not on the main tourist strips. Visit the Chapin Memorial Library in downtown Myrtle Beach, stop by a farmers market, and attend a community event if timing allows. These experiences reveal the texture of a community in ways that no real estate brochure can replicate.

In the latter half of your visit, begin scheduling appointments with real estate agents and attending open houses. Come prepared with your budget, financing pre-approval if possible, and a clear list of must-haves versus nice-to-haves. Bring a notebook or use a property tracking app to record your impressions of each neighborhood and home you visit.

Finally, take time to speak with current residents. Strike up conversations at coffee shops, on the beach, at the golf course. Ask people what they love about living there and what they wish they had known before moving. These candid conversations are among the most valuable research tools available to any prospective buyer.

Conclusion and Call to Action: Your Next Chapter Starts with a Visit

Myrtle Beach is more than a beach town. It is a dynamic, growing community with a real estate market that rewards informed buyers, a lifestyle that suits retirees, families, and investors alike, and a natural beauty that simply does not get old. Whether you are dreaming of a vacation rental that pays for itself, a retirement home where every morning begins with an ocean sunrise, or a permanent coastal lifestyle, Myrtle Beach deserves serious consideration.

The first and most important step is to go see it for yourself. Plan your trip, explore the neighborhoods, talk to the locals, walk the beaches, and eat the seafood. Let the place speak to you before you let the listings do the talking.


When you are ready to move from visitor to property owner, connect with a local real estate professional who knows the Grand Strand inside and out. Request a market analysis for the neighborhoods that interest you most, attend open houses with clear intention, and do not rush the process. The right property in the right community is worth taking the time to find.

Posted in BoydTeam Blog
June 3, 2026

How Upgrading Your HVAC System Boosts Your Home’s Resale Value

When preparing a house for the real estate market, homeowners often focus on highly visible cosmetic upgrades. They repaint the walls in trendy neutral colors, replace dated kitchen countertops, and invest heavily in landscaping to maximize curb appeal. While these aesthetic improvements certainly attract buyers during an open house, they only scratch the surface of what modern home buyers truly prioritize.

In the current real estate market, buyers are increasingly analytical and risk-averse. They look beyond the surface level to evaluate a property’s underlying infrastructure. Among these structural components, the heating, ventilation, and air conditioning (HVAC) system stands out as one of the most critical. A home’s mechanical backbone dictates daily comfort, monthly utility expenses, and imminent maintenance burdens. Upgrading your climate control system before listing your property is not merely a maintenance task; it is a strategic investment that can significantly enhance your home's equity, marketability, and final sale price.

1. Direct Equity and High Return on Investment

One of the most pressing questions for any homeowner considering a major renovation is the financial return. Fortunately, mechanical upgrades consistently rank high in terms of value retention. Real estate data indicates that a new climate control system can yield a return on investment that frequently rivals or surpasses traditional cosmetic remodels. When a buyer views a property with a brand-new heating and cooling system, they immediately factor that asset into their financial offer.

This premium exists because a new system eliminates a massive, immediate expense for the incoming homeowner. Replacing a furnace or an outdoor compressor unit is a costly endeavor that can easily drain a buyer's post-closing cash reserves. By taking care of this upgrade yourself, you allow buyers to bid with confidence. They know they will not have to shell out thousands of dollars during their first winter or summer in the home.

Furthermore, licensed appraisers explicitly look at the age and condition of major mechanical systems when determining a property's fair market value. An outdated, failing furnace acts as a deduction during the valuation process. Conversely, a state-of-the-art system in peak operational condition justifies a higher baseline valuation. This formal increase in appraised value gives your listing a solid mathematical foundation, which protects your asking price when the buyer's mortgage lender conducts their independent property assessment.

2. Lower Utility Bills as a Major Selling Point

Modern home buyers are uniquely focused on the ongoing cost of homeownership, with energy efficiency sitting at the very top of their wish lists. Utility bills represent a recurring monthly expense that directly impacts a household's disposable income. Consequently, a property that promises lower monthly operating costs holds a distinct competitive advantage over older, less efficient homes.

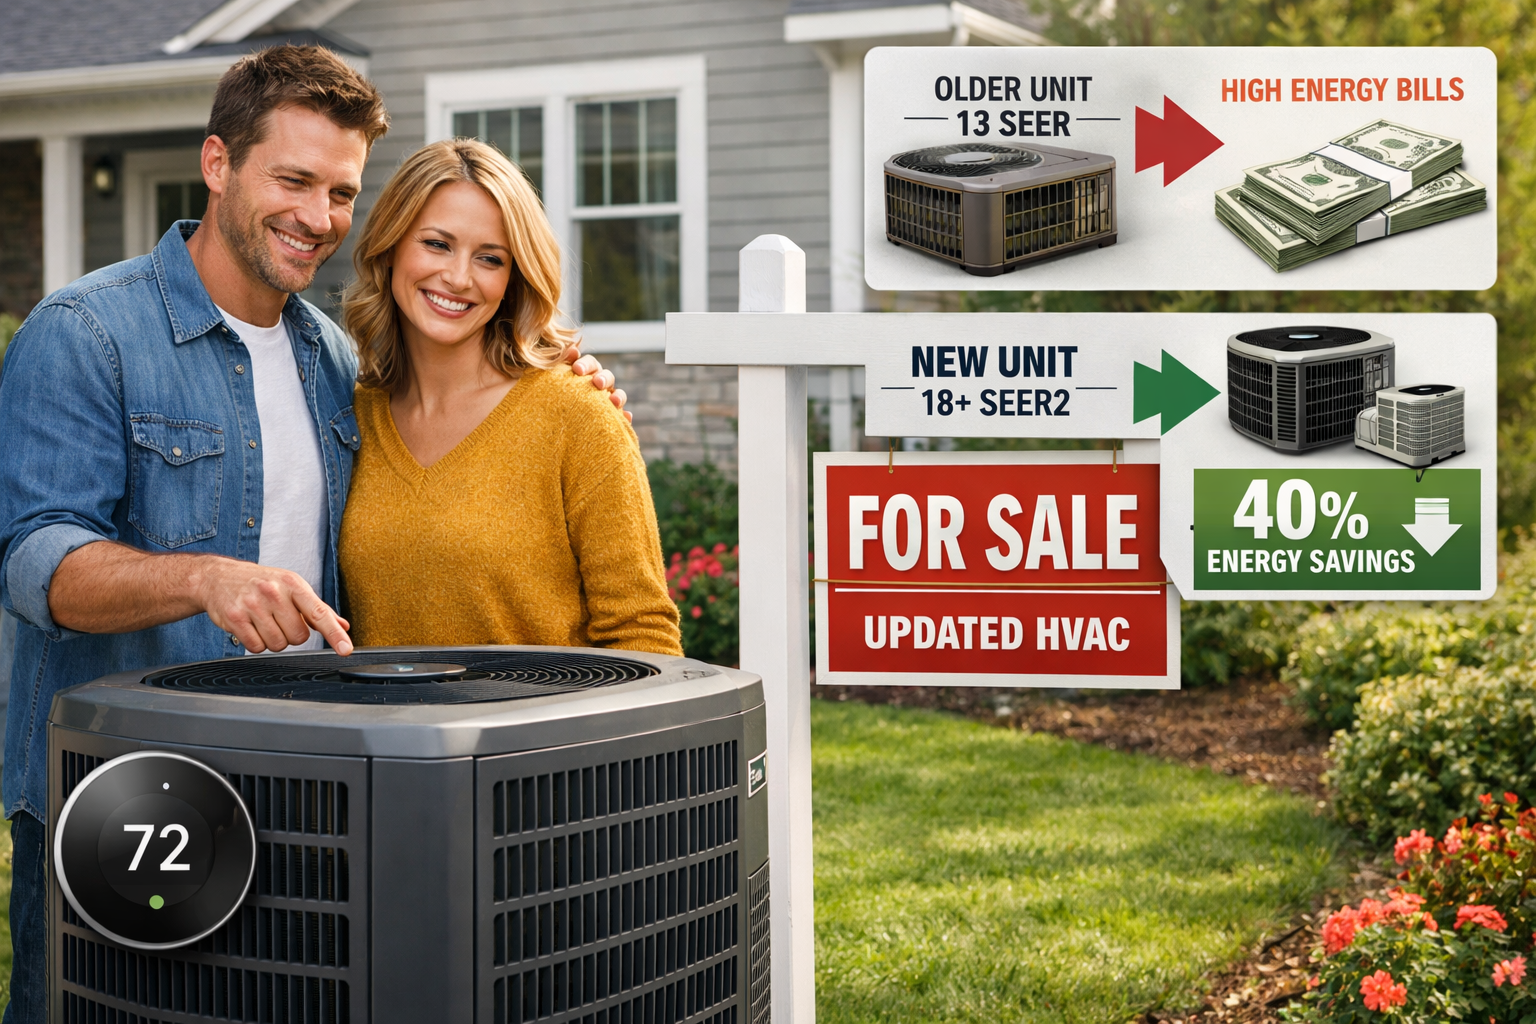
Older heating and cooling units operate with significantly lower efficiency ratings compared to contemporary models. System efficiency is measured by specific industry standards, such as the Seasonal Energy Efficiency Ratio (SEER2) for air conditioners and the Annual Fuel Utilization Efficiency (AFUE) for furnaces. Systems manufactured just a decade ago often have SEER ratings around 13 or 14. In contrast, modern high-efficiency units frequently reach SEER2 ratings well above 18 or 20.

[Older Standard Unit] ---> ~13-14 SEER ---> Higher Monthly Waste

[Modern Upgraded Unit] ---> 18+ SEER2   ---> Up to 40% Energy Savings

When you upgrade to a high-efficiency system, you gain a powerful marketing tool for your real estate listing. Your real estate agent can prominently feature the energy savings in the property description, and you can even provide copies of recent, lowered utility bills during home tours. Buyers love concrete data. Seeing physical proof that your home costs 30% to 40% less to heat and cool than a comparable house down the street creates a powerful incentive to choose your property.

3. Minimizing Home Inspection Friction

The period between accepting an offer and officially closing the sale is often the most stressful phase of a real estate transaction. This phase is dominated by the home inspection, where a licensed inspector meticulously evaluates every nook and cranny of your property to uncover hidden defects. Historically, aging mechanical systems are among the most common culprits for derailed sales or aggressive price renegotiations.

If an inspector flags an HVAC system as near the end of its operational lifespan, cracked, or leaking, the buyer's momentum often grinds to a halt. This negative report triggers a series of complications:

  • Price Reductions: Buyers may demand a massive price concession to cover the future replacement cost.
  • Repair Demands: Buyers might insist that the system be fully replaced by a contractor of their choosing before closing, stripping away your control over the project's timeline and budget.
  • Transaction Cancellations: Skittish buyers may simply use the defective system as a justification to invoke their inspection contingency and walk away from the deal entirely.

By proactively upgrading the system before your home ever hits the market, you completely neutralize this risk. The home inspector will note the brand-new equipment, clean ductwork, and flawless operation in their official report. Instead of a liability that invites aggressive bargaining, your mechanical system becomes a verified asset that solidifies the agreed-upon purchase price.

4. Enhanced Indoor Comfort and Intelligent Home Appeal

While financial returns and technical specifications look excellent on paper, the emotional aspect of buying a home should never be underestimated. When prospective buyers walk through an open house, they are unconsciously evaluating how it feels to live in those spaces. An upgraded climate control system transforms the sensory experience of a home.

Modern systems do far more than just modify the air temperature; they completely revolutionize indoor air quality and humidity control with air duct cleaning. Variable-speed blowers and advanced filtration systems remove dust, pollen, and pet dander continuously, which creates a noticeably fresher indoor atmosphere. Furthermore, contemporary units excel at balancing temperatures across different floors, eliminating the frustrating phenomenon of a freezing basement and a sweltering second story.

The Smart Home Advantage: Modern systems easily integrate with intelligent thermostats and home automation networks.

When buyers see a sleek, smart thermostat on the wall that allows them to control zonal temperatures via a smartphone app, the property instantly feels premium and forward-thinking. This integration appeals heavily to millennial and Generation Z buyers, who now make up the largest demographic of home shoppers. They view smart, healthy home features not as luxury bonuses, but as fundamental expectations for their next living space.

Conclusion and Next Steps

In the competitive world of real estate, securing a premium sale price requires strategic planning and targeted investments. While visual remodels have their place, upgrading an aging HVAC system offers a multi-layered financial defense. It raises your home's appraised equity, lowers monthly operating costs for the future owner, eliminates friction during the crucial home inspection phase, and provides a tangible sense of comfort that buyers can feel the moment they step through your front door.

If your current heating and cooling units are approaching or exceeding ten years of age, scheduling a professional consultation should be your next priority. Investing in a modern, high-efficiency system today ensures that your property stands out as a premium, worry-free listing tomorrow. Reach out to a licensed HVAC professional in your area to evaluate your home's current needs, explore energy-efficient options, and position your property for maximum profit in today's demanding real estate market.

Posted in BoydTeam Blog
April 21, 2026

How Moving Midlife Can Transform Your Life and Lifestyle

Midlife adults craving lifestyle reinvention often feel stuck between what looks fine on paper and what no longer fits day to day. The tension is real: a move can open doors to a career change and a better pace of living, yet it can also stir up doubts about stability, identity, and starting over. Seen through a different lens, relocation becomes midlife transition empowerment, a chance to choose a place that supports who someone is becoming, not just who they’ve been. With the right mindset, moving can be a clean moment for personal goal resetting.

Understanding the Midlife Move Mindset

A midlife move becomes transformative when you treat it as a values-based decision, not a panic button. The mindset is simple: connect the practical upsides of relocating to personal growth, so you choose change from clarity instead of fear. A move works best when it supports how you work, how you live, and who you are becoming.

This matters because pressure creates rushed choices, while confidence creates options. When your “why” is clear, tradeoffs feel manageable, from commute time to friendships to finances. It also keeps you from chasing someone else’s version of success.

Think of it like updating a map, not fleeing a storm. You name what you want daily life to feel like, then pick a place that makes that rhythm easier.

That clarity can guide home criteria, neighborhood fit, and long-term value stability.

Choose a Home and Neighborhood That Fit the New You

A midlife move is easiest to sustain when your home and neighborhood do the supporting, not the other way around. Use these real estate considerations to turn your new priorities into concrete, livable choices.

  1. Write your “midlife-alignment” home criteria (then rank it): Start with two lists: Must-haves (non-negotiable) and Nice-to-haves (bonuses). Keep it practical, think single-floor living, a dedicated office, a low-maintenance yard, or a kitchen that supports healthier routines. Rank the top 5 must-haves so you can make confident tradeoffs when a house is great in one area but weaker in another.

  2. Map your everyday amenities within a 15-minute radius: Choose 5–8 weekly anchors, grocery store, primary care, gym/walking trail, library, faith/community center, coffee shop, or caregiving routes, and test-drive them from each neighborhood you’re considering. Do one weekday commute run and one weekend errand loop to see traffic, noise, and parking reality. This turns “nice neighborhood vibe” into measurable lifestyle alignment.

  3. Buy for stability, not just charm: For property value stability, look for “consistent demand” signals: reasonable school ratings if relevant to your buyer pool, proximity to major employers/health systems, low vacancy, and well-kept nearby homes. Ask what’s changing: new zoning, planned developments, or upcoming road projects can help or hurt future resale. If you’re unsure, request a comparative market analysis so you can compare recent sold prices and avoid paying a “hope premium.”

  4. Inspect the home through the lens of time, energy, and maintenance: Walk every property asking, “What will this require from me each month?” Note roof age, HVAC age, windows, drainage, and the size of the yard or snow/leaf workload. If you want less mental load, plan a simple system. Many homeowners use reminders, shared calendars, and simple lists to keep maintenance predictable instead of reactive.

  5. Check community engagement before you commit: Community isn’t automatic, you can screen for it. Visit neighborhood associations, community boards, and local event calendars; then take a walk at two different times of day and notice whether people are outside, greeting each other, or using shared spaces. If connection is part of your reset, prioritize places with “light-touch belonging” options like volunteer days, walking groups, or a community garden.

  6. Pressure-test affordability with a “career-flex” budget: Even if you’re not changing jobs yet, plan for flexibility: estimate housing costs plus utilities, insurance, and maintenance, then see how it feels on a conservative income scenario for 6–12 months. This protects the mindset you’re building, choices made from clarity beat choices made from urgency. These steps make it easier to compare financing, timelines, and career options with confidence.

Common Questions About Moving in Midlife

Quick clarity for the questions most people carry.

Q: What are the key lifestyle benefits of making a move in midlife to start fresh?
A: A midlife move can create space for healthier routines, stronger community ties, and a home that fits how you live now. It also gives you a clean reset on habits, schedules, and even identity, without having to “push through” old patterns. Start by naming the 3 outcomes you want most, like more time, connection, or calm, and let those guide decisions.

Q: How can someone overcome feelings of uncertainty and stress when relocating at this stage in life?
A: Uncertainty is normal when you are changing both place and purpose, so focus on what you can control this week. Build a simple plan that includes money, support, and timelines, because financial planning needs to adapt when life is in transition. One grounding step is to schedule two “reality checks” each month with a friend, coach, or partner to talk through fears and next actions.

Q: What practical real estate factors should be considered to find a home and neighborhood that truly support new personal goals?
A: Look past surface appeal and measure daily fit: walkability, noise, commuting time, healthcare access, and maintenance load. Ask for insurance, utility, and repair expectations up front so the home supports your energy, not drains it. If you want financial flexibility, consider whether tax loss harvesting could be relevant before major financial decisions, then confirm with a qualified professional.

Q: How can simplifying your living environment through a move help redefine your daily routines and reduce overwhelm?
A: Moving is a natural editing point, so it is easier to release items, commitments, and spaces that no longer match your priorities. A smaller or more functional layout can turn “maintenance mode” into “life mode,” making routines like cooking, movement, and rest more automatic. Try a one-box rule: pack one box of “day-one essentials” that reflects the life you want to live.

Q: If I want to pursue a new career path after relocating, what kinds of educational opportunities should I explore to gain relevant skills?
A: Start with learning that fits real life: short certificate programs, community college pathways, apprenticeships, or flexible online degrees, including computer science degree pathways. If an IT shift is part of your plan, prioritize skills-based coursework in areas like support, data, cybersecurity, or cloud fundamentals, plus portfolio projects. Choose programs with clear outcomes and a schedule you can sustain during the move.

You do not need perfect certainty, just a plan you can keep refining.

Midlife Move Planning Checklist

Keep the momentum going:

This checklist turns big feelings into a few clear moves you can finish in a weekend. Use it to keep your midlife relocation focused on daily life improvements, not just a new address.

✔ Define your top 3 outcomes for the next chapter

✔ Set a budget range and monthly comfort number

✔ Compare neighborhoods using walkability, noise, care access, and commute

✔ Confirm true housing costs: insurance, utilities, repairs, taxes, fees

✔ Create a timeline with weekly tasks and two monthly support check-ins

✔ Pack a day-one essentials box to protect routines immediately

✔ Schedule learning or job-search blocks that fit your moving weeks

Small steps, done in order, make the new life feel real faster.

Turning a Midlife Move Into Confident New Beginnings


Midlife relocation can feel like choosing between the comfort of what’s known and the pull of what’s next. The steadier path is treating the move as a values-led plan, rooted in clarity, realistic planning, and empowerment through change, rather than a leap made in exhaustion or fear. When that mindset guides the decisions, midlife transformation becomes less about loss and more about embracing new opportunities, building confidence in relocation, and creating positive life transitions that fit the life being lived now. A midlife move isn’t an escape, it’s a decision to live with intention. Choose one action today: research a neighborhood, talk to a lender, or write down the three priorities that matter most. That first small step builds resilience and connection, turning uncertainty into a steadier sense of home.

Posted in BoydTeam Blog