CATCH THE WAVE

Myrtle Beach Real Estate

We Specialize in Myrtle Beach, SC Real Estate. Lots of options are waiting for you in Myrtle Beach, South Carolina and choosing the right realtors can help you in finding the perfect area and the right home for you and your family and make your dream a reality!  Let us help you in making one of the biggest, if not the biggest, decisions in your life.   

We were both born and raised along the Grand Strand and know the entire Horry County, so no matter what style of home you are looking for or what area you prefer, we can help you!  Please give us a call and let us help you make your dream a reality!  843-222-8566.

Eddie & Julie Boyd - The Boyd Team - Realtors

Myrtle Beach Real Estate - INNOVATE Real Estate


May 20, 2019

Things To Repair Before You List Your Home For Sale

When you’re getting ready to list your home, it’s of the utmost importance to ensure you are showing it in the best light. Taking time to highlight its strengths and fix up some of its possible weaknesses can make a big difference in how fast it sells. Here are our top five recommended repairs to make before selling your home.

Repaint walls.

Giving your home a fresh coat of paint is one of the most cost-effective ways to spruce it up, and generally, it can be a do-it-yourself project. Make sure to cover any walls with scratches and chips and consider updating any accent walls with a more neutral coat.

Repair floors.

Hardwood floors are a very desirable feature in a home, so you want to ensure they look their best by fixing scratches or dull areas. If your carpet is worn or stained, consider replacing them. And don’t forget the tile in your kitchen or bathrooms. Re-grouting can go a long way in making dingy tile work look brand new!

Refresh the landscaping.

Show buyers your home is the full package by dressing up the outside as well as the in. Clean walkways and driveways, plant seasonal flowers and plants, trim hedges and trees, install outdoor décor pieces and fill in mulch and gravel.

Fix your fixtures.

Leaky faucet? Rusted drains? Does loose drawer handle? Making these small fixes can make a big difference to potential buyers with detailed-orientated minds. Improve your kitchen. An outdated kitchen can be a real eyesore in a home. Updating cabinetry, repairing or replacing countertops, and installing new faucets and sinks may be worth the investment.


Posted in BoydTeam Blog
May 17, 2019

A Careful, Thoughtful Process: Downsizing Advice for Seniors

Moving to a new home is always an anxious and stressful experience, no matter how many times you’ve done it. It means leaving memories behind and starting a new life in a new location. For an older adult, it can be downright traumatic. Making such a profound change late in life, even a beneficial change, is no small matter.

Downsizing, however it occurs, is an inevitable change for seniors when they’ve reached a point where living in a home that’s too large for them is no longer possible. Maintenance and cleaning become too much to handle and downsizing becomes a necessity.

But moving to a smaller living space requires the elimination of many objects, some of which you may be strongly attached to. Deciding what goes and what stays takes some time and shouldn’t be done lightly. It’s a trying experience, and it’s important to be physically and emotionally prepared.  

Don’t waste time

As soon as you know you’ll be moving, begin sorting your belongings, preferably with a close friend or family member who can provide emotional and physical support. Waiting too long can put you in a difficult situation where you’re more likely to make a hasty decision because time is short. At the very least, you’ll want two full weeks in which to go through everything. Senior move experts advise that each item under consideration should be handled and considered before you decide whether to keep or get rid of it. Go room by room rather than attacking the whole house at once, and begin with a small room so you don’t feel overwhelmed right from the start.

Keep your new space in mind 

Downsizing means less square footage and probably less storage space than you’re used to. It also means there are fewer rooms to fill now, which means getting rid of a substantial number of belongings. You no longer need three or four guest bedrooms, so you can count on getting rid of items from those rooms right off the top. As you create a “get-rid-of” pile, consider how you’ll dispose of it all. Simply laying it all out for the trash collectors to haul away isn’t an environmentally responsible act.

Decide which objects can be given to other family members, what could be sold through consignment, and what can be donated to charitable organizations. If you’re getting rid of large furniture, mattresses or clothing, remember that the material of which they’re made can be recovered at special recycling centers.

The right home for you

In addition to downsizing, this is an opportunity to do something you’ve always wanted to, like live in a wooded area, near a lake or the ocean, or closer to loved ones. Of course, your first considerations should be your needs and whether it makes sense to purchase a new house, an apartment, or move into an assisted living facility.

If you’re relocating to a new, smaller house, it should be one that offers ease of movement and accessibility if you have restricted mobility and, above all, it should be a safe living environment. You also want to get the best price possible. Take a look at the home values and prices in the area where you’re moving to make sure you’re getting the right house at the right price (average home prices in Myrtle Beach were purchased at an average of $182,000 over the past 30 days).

Moving

Finding the right moving company, one you can be sure will safeguard your belongings, requires some online research. If necessary, seek the help of a relative who can assist you in your search and in finding a company that has experience working with seniors. Bear in mind that senior move managers are widely available experts who understand the special needs of older adults and the particular challenges they face. A senior move manager can tackle a lot of the planning legwork so you can focus on more important tasks.

It’s natural to want to get a difficult situation like downsizing and moving over with as soon as possible. And while you should begin downsizing as soon as you know you’re moving, you need the time to do it properly so you don’t make hasty decisions you’ll regret later. Approach it as a process requiring thought and energy and all will be well.


Posted in BoydTeam Blog
May 16, 2019

Home-Buying Tips for Savvy Seniors


Regardless of your age, the decision to move is never an easy one. However, it’s an even tougher one as you enter retirement. Not only do you have to consider proximity to your loved ones, but it will also be necessary to plan ahead for mobility issues that often accompany age. Here are a few tips to help you make the most of what will hopefully be your last move.


Partner with the Right Realtor


When it comes to buying — and selling — not all agents are created equally. Choosing the right agent is essential during your senior years, even more so if you are unfamiliar with the area in which you are relocating. Zillow smartly recommends interviewing multiple agents. These interviews should be followed up by checking their ratings and recommendations. Don’t be afraid to ask for references. Other questions to ask include:


      How long have you lived in the area?

      How many other clients are you currently working with?

      Do you have experience helping seniors purchase a home for retirement?


You want an agent that knows the ins and outs of the local market and can point out any potential areas of interest, including medical facilities, golf courses, and senior service agencies. It’s also wise to choose an agent who limits the number of clients with whom they contract since you need someone who can be responsive and attentive to your needs. Finally, choosing someone who has experience with people in your particular demographic means they won’t try to push the first family home that’s available.


Don’t Settle for Just Any Loan


Chances are, you will have multiple financing options to choose from. Avoid the temptation to sign on just any loan, however, as you could be wasting money. Instead, consider your options carefully. If you are a veteran, don’t overlook a VA loan, which, according to PennyMac Loan Services, is different from a conventional or FHA loan. First, you will not be required to come up with a down payment, and you don’t have to pay PMI. VA loans typically have lower interest rates and are guaranteed to close on time as long as the agreed-upon sales price is the same or less than the property’s appraised value.


Consider Your Future Needs


Even if you think of age as nothing but a number, you cannot deny the fact that nearly four out of 10 seniors — which are considered persons aged 65 and older — have at least one disability. When you are shopping for a home, look for a property that will accommodate your potential future health. A single-story home is a popular and practical choice for seniors. You will also want to look for a home with a bathroom wide enough to accommodate a walker with enough wall space to add grab bars if necessary. ConsumerAffairs.com offers more information about aging-in-place modifications that will allow you to remain independent for as long as possible.


Don’t DIY Moving Day


Once you have found the right realtor, secured financing, and made your needs and wants known, it’s time to consider how you will actually complete the task of moving. If you are looking to save money, it’s understandable that you don’t want to pay for movers. However, your best bet may be to find a moving company that specializes in senior downsizing. You can also enlist the help of friends and family to help you sort and organize your current home well ahead of the big day. This will give you a head start and, more importantly, an opportunity to bond with those you love while going through the memories you’ve made in your current home.


Moving, especially to a smaller home, can be a daunting process, but it’s one that comes with many rewards. Finding a new place to settle down can free up time for you to pursue other endeavors while making it possible to remain independent well beyond your 65th birthday.


Image via Pixabay

Posted in BoydTeam Blog
May 14, 2019

Investing In Real Estate

Investing in real estate is one of the oldest forms of investing, having been around since the early days of human civilization. Predating modern stock markets, real estate is one of the five basic asset classes that every investor should seriously consider adding to his or her portfolio for the unique cash flow, liquidity, profitability, tax, and diversification benefits it offers. In this introductory guide, we'll walk you through the basics of real estate investing, and discuss the different ways you might acquire or take ownership in real estate investments.

First, let's start with the basics: What is real estate investing?

What Is Real Estate Investing?

Real estate investing is a broad category of operating, investing, and financial activities centered around making money from tangible property or cash flows somehow tied to a tangible property.

There are four main ways to make money in real estate:

  1. Real Estate Appreciation: This is when the property increases in value. This may be due to a change in the real estate market that increases demand for property in your area. It could use be due to upgrades you put into your real estate investment to make it more attractive to potential buyers or renters. Real estate appreciation is a tricky game, though.
  2. Cash Flow Income (Rent): This type of real estate investment focuses on buying a real estate property, such as an apartment building, and operating it so you collect a stream of cash from rent. Cash flow income can be generated from apartment buildings, office buildings, rental houses, and more.
  3. Real Estate Related Income: This is income generated by brokers and other industry specialists who make money through commissions from buying and selling property. It also includes real estate management companies who get to keep a percentage of rents in exchange for running the day-to-day operations of a property.
  1. Ancillary Real Estate Investment Income: For some real estate investments, this can be a huge source of profit. Ancillary real estate investment income includes things like vending machines in office buildings or laundry facilities in low-rent apartments. In effect, they serve as mini-businesses within a bigger real estate investment, letting you make money from a semi-captive collection of customers.

The purest, simplest form of real estate investing is all about cash flow from rents rather than appreciation. Real estate investing occurs when the investor, also known as the landlord, acquires a piece of tangible property, whether that's raw farmland, land with a house on it, land with an office building on it, land with an industrial warehouse on it, or an apartment.

He or she then finds someone who wants to use this property, known as a tenant, and they enter into an agreement. The tenant is granted access to the real estate, to use it under certain terms, for a specific length of time, and with certain restrictions -- some of which are laid out in Federal, state, and local law, and others of which are agreed upon in the lease contract or rental agreement. In exchange, the tenant pays for the ability to use the real estate. The payment he or she sends to the landlord is known as "rent".

For many investors, rental income from real estate investments has a huge psychological advantage over dividends and interest from investing in stocks and bonds. They can drive by the property, see it, and touch it with their hands. They can paint it their favorite color or hire an architect and construction company to modify it. They can use their negotiation skills to determine the rental rate, allowing a good operator to generate higher capitalization rates, or "cap rates."

From time to time, real estate investors become as misguided as stock investors during stock market bubbles, insisting that capitalization rates don't matter. Don't fall for it. If you are able to price your rental rates appropriately, you should enjoy a satisfactory rate of return on your capital after accounting for the cost of the property, including reasonable depreciation reserves, property and income taxes, maintenance, insurance, and other related expenditures. Additionally, you should measure the amount of time required to deal with the investment, as your time is the most valuable asset you have -- it's the reason passive income is so cherished by investors. (Once your holdings are large enough, you can establish or hire a real estate property management company to handle the day-to-day operations of your real estate portfolio in exchange for a percentage of the rental revenue, transforming real estate investments that had been actively managed into passive investments.)

What Are Some of the Most Popular Ways for a Person to Begin Investing in Real Estate?

There is a myriad of different types of real estate investments a person might consider for his or her portfolio.

It's easier to think in terms of the major categories into which real estate investments fall based on the unique benefits and drawbacks, economic characteristics and rent cycles, customary lease terms, and brokerage practices of the property type. Real estate properties are ordinarily categorized into one of the following groups:

  • Residential real estate investing - These are properties that involve investing in real estate tied to houses or apartments in which individuals or families live. Sometimes, real estate investments of this type have a service business component, such as assisted living facilities for seniors or full-service buildings for tenants who want a luxury experience. Leases usually run for 12 months, give or take six months on either side, leading to a much more rapid adjustment to market conditions than certain other types of real estate investments.
  • Commercial real estate investing - Commercial real estate investments largely consist of office buildings. These leases can be locked in for many years, resulting in a double-edged sword. When a commercial real estate investment is fully leased with long-term tenants who agreed to richly priced lease rates, the cash flow continues even if the lease rates on comparable properties fall (provided the tenant doesn't go bankrupt). On the other hand, the opposite is true - you could find yourself earning significantly below-market lease rates on an office building because you signed long-term leases before lease rates increased.
  • Industrial real estate investing - Properties that fall under the industrial real estate umbrella can include warehouses and distribution centers, storage units, manufacturing facilities, and assembly plants.
  • Retail real estate investing - Some investors want to own properties such as shopping centers, strip malls, or traditional malls. Tenants can include retail shops, hair salons, restaurants, and similar enterprises. In some cases, rental rates include a percentage of a store's retail sales to create an incentive for the landlord to do as much as he, she, or it can to make the retail property attractive to shoppers.
  • Mixed-use real estate investing - This is a catch-all category for when an investor develops or acquires a property that includes multiple types of the aforementioned real estate investments. For example, you might build a multi-story building that has retail and restaurants on the ground floor, office space on the next few floors, and residential apartments on the remaining floors.

You can also get involved on the lending side of real estate investing by:

  • Owning a bank that underwrites mortgages and commercial real estate loans. This can include public ownership of stocks. When an institutional or individual investor is analyzing a bank stocks, it pays to pay attention to the real estate exposure of the bank loans.
  • Underwriting private mortgages for individuals, often at higher interest rates to compensate you for the additional risk, perhaps including a lease-to-own credit provision.
  • Investing in mezzanine securities, which allows you to lend money to a real estate project that you can then convert into equity ownership if it isn't repaid. These are sometimes used in the development of hotel franchises.

There are sub-specialties of real estate investing including:

  • Leasing a space so you have little capital tied up in it, improving it, then sub-leasing that same space to others for much higher rates, creating incredible returns on capital. An example is a well-run flexible office business in a major city where smaller or mobile workers can buy office time or rent specific offices.
  • Acquiring tax-lien certificates. These are an esoteric area of real estate investing and not appropriate for hands-off or inexperienced investors but which -- under the right circumstances, at the right time, and with the right sort of person -- generate high returns to compensate for the headaches and risks involved.

Real Estate Investment Trusts (REITs)

On top of all of this, you can actually invest in real estate through something known as a real estate investment trust, or REIT. An investor can buy REITs through a brokerage accountRoth IRA, or another custody account of some sort. REITs are unique because the tax structure under which they are operated was created back during the Eisenhower administration to encourage smaller investors to invest in real estate projects they otherwise wouldn't be able to afford, such as building shopping centers or hotels. Corporations that have opted for REIT treatment pay no Federal income tax on their corporate earnings as long as they follow a few rules, including a requirement to distribute 90% or more of profits to shareholders as dividends.

One downside of investing in REITs is that, unlike common stocks, the dividends paid out on them are not "qualified dividends", meaning the owner can't take advantage of the low tax rates available for most dividends. Instead, dividends from real estate investment trusts are taxed at the investor's personal rate. On the upside, the IRS has subsequently ruled that REIT dividends generated within a tax shelter such as a Rollover IRA are largely not subject to the unrelated business income tax so you might be able to hold them in a retirement account without much worry of tax complexity, unlike a master limited partnership.

(If you're interested in learning more about these unique securities, start by checking out Real Estate Investing Through REITswhich covers REIT liquidity, equity, how to use REITs to your real estate investing advantage, and much more.)

Investing in Real Estate Through Home Ownership

For all the real estate investing options available to investors, the average person is going to get his or her first real estate ownership experience the traditional way: By purchasing a home.

I've never viewed the acquisition of a home quite the same way most of society does. Instead, I prefer to think of a person's primary residence as a blend of personal utility and financial valuation, and not necessarily an investment. To be more direct, a home isn't an investment in the same way an apartment building is. At its very best, and under the most ideal of circumstances, the safest strategy is to think of a home as a type of forced savings account that gives you a lot of personal use and joy while you reside in it.

On the other hand, as you approach retirement, if you take a holistic view of your personal wealth, outright ownership of a home (without any debt against it) is one of the best investments a person can make. Not only can the equity be tapped through the use of certain transactions, including reverse mortgages, but the cash flow saved from not having to rent generally results in net savings -- the profit component that would have gone to the landlord effectively stays in the homeowner's pocket. This effect is so powerful that even back in the 1920s economists were trying to figure out a way for the Federal government to tax the cash savings over renting for debt-free homeowners, considering it a source of income.

This is a different type of investment, though -- something known as a "strategic investment." Were the economy to collapse, as long as you could pay the property taxes and basic upkeep, no one could evict you from your home. Even if you had to grow your own food in a garden, there's a level of personal safety there that matters. There are times when financial returns are secondary to other, more practical considerations. Whatever you do, though, don't sacrifice your liquidity to try and build equity in your real estate investments too quickly, as that can lead to disaster (including bankruptcy).

If you are saving to acquire a home, one of the big mistakes I see is new investors putting their money into the stock market, either through individual stocks or index funds. If you have any chance of needing to tap your money within five years or less, you have no business being anywhere near the stock market. Instead, you should be following an investment mandate known as capital preservation. Here are the best places to invest money you're saving for a down payment.

Which Is Better - Real Estate Investing or Investing in Stocks?

One of the most common questions I encounter involves the relative attractiveness of investing in stocks versus investing in real estate. The short version is that it's somewhat akin to comparing vanilla and chocolate ice cream. They are different, and as your net worth grows, you may even find that both have a role to play in your overall portfolio. Your personality will also inform your decision, as some people are more temperamentally geared toward stock ownership or real estate ownership, respectively.

Risks of Real Estate Investing

A substantial percentage of real estate returns are generated due to the use of leverage. A real estate property is acquired with a percentage of equity, the remainder financed with debt. This results in higher returns on equity for the real estate investor; but if things go poorly, it can result in ruin far more quickly than a portfolio of fully-paid common stocks. (That's true even if the latter declined by 90% in a Great Depression scenario, as no one could force you to liquidate).

That's why the most conservative real estate investors insist upon a 50% debt-to-equity ratio or, in extreme cases, 100% equity capital structures, which can still produce good returns if the real estate assets have been selected wisely. Billionaire Charlie Munger talks about a friend of his prior to the 2007-2009 real estate collapse. This friend, a very rich landlord in California, looked around at the high valuations on his properties and said to himself: "I'm wealthier than I would ever need to be. There's no reason for me to take risks for the sake of more." This friend sold many of his properties and used the proceeds to pay off the debt on the remaining ones that he thought the most attractive. As a result, when the economy collapsed, the real estate markets were in turmoil, people were losing their properties to foreclosure, and bank stocks were collapsing -- he didn't have to worry about any of it. Even as rents dropped due to tenant financial difficulties, it was all still surplus cash and he was armed with funds that kept replenishing themselves, letting him take advantage of buying up the assets everyone else was forced to sell.

Stop trying to get rich so quickly, and be content to do it the right way. You'll have much less stress in your life, and it can be a lot of fun.

Some Final Thoughts on Real Estate Investing

Of course, this is only the beginning of your journey to understanding the topic, as we've barely scratched the surface. Real estate investing takes years of practice, experience, and exposure to truly appreciate, understand, and master.

#myrtlebeach #realestate #boydteam #results #werockthebeach

Posted in BoydTeam Blog
May 10, 2019

Low-Cost Kitchen Improvements for Any Home

Not every home owner can splurge on a total upscale kitchen redo, now pegged on average at $111,000, according to the latest Cost vs. Value Report from Remodeling magazine. Many home owners don’t even have the funds for a minor kitchen remodeling project, which is placed at around $20,000.

But a lack of funds isn’t necessarily the only issue. Even home owners with fat wallets and a love of congregating and cooking in a stylish kitchen may not want to invest so much, given the up-and-down nature of today’s housing market.

Specifically, two factors are holding back home owners from taking on kitchen redos:

▪ There’s no guarantee that prospective buyers will like, say, the sellers’ tangerine-painted walls — even if orange is oh-so-chic these days — or that a restaurant-style range will win them over, especially if they’re better at calling for reservations or take-out.

▪ The dollars invested may never be recouped, no matter how long home owners stay put. An upscale overhaul will return only about 57 percent of the money spent on the project, and a mid-range redo about 66 percent, according to the Cost vs. Value Report.

But the good news for those who still feel their current kitchen won’t do is that there’s loads of inspiration to appeal and borrow ideas from — those handsome rooms shown in the background of Food Network programs and other TV shows and movies, for example, or glossy home and design magazines.

The kitchen remains an important gathering space for many home owners — and one of the first places would-be-buyers look to decide if they’re interested in a purchase. Because of that, it should be a goal to make the kitchen as nice as possible with the funds at hand. Even if a seller or real estate agent has $20,000, $10,000, or just $5,000 to spend, those dollars can deliver a lot to make the kitchen look and function better.

Here are a dozen low-cost ideas you and your clients can use to improve this critical room:

▪ Paint remains the least expensive change agent. Home owners should take their cue from other colors in the room that are likely to stay — the “nonperishables,” says Chicago-based designer Mary Lou Kalmus. It might come from the backsplash or floor tile, or if the entire room is swathed in neutrals, it could be colors in the rest of the house, such as in an adjacent family room. Because the kitchen gets heavy use, it’s best if they use at least an eggshell rather than a flat finish.

▪ Backsplash tiles can be replaced, but Kalmus suggests home owners do so from the base of the upper cabinets down to the countertop — a full 18 inches is recommended. Top on her list of favorite choices are glass or newer-looking metallic tiles. She also suggests running them vertically rather than horizontally for a less-expected look.

▪ Replacing a countertop or two can help a room make an instant, fresh impression. And if money’s tight, home owners can go with a laminate rather than granite. To prevent laminate from scratching or showing burn marks, a textured choice is best.

▪ Tell clients to go with decor icons such as stainless steel that tend to appeal universally, says design expert and author Christopher Lowell, based in Santa Fe, N.M. They can start by replacing some dated and dysfunctional appliances with purchases at places like Sears or Costco, which offer professional-style models that bring a restaurant look at affordable prices. Once home owners introduce stainless options, they may want to run with the idea throughout — e.g., paper towel holders, trash cans, and cookware, Lowell says.

▪ If all the older appliances can’t be replaced, home owners might be wise to focus on one or two, which can still make a difference. Because the refrigerator may be the largest item in the room, Kalmus suggests changing it first if it’s old or small and considering a model with French doors, which offers the plus of storing larger items inside both the refrigerator and freezer sections and having a freezer on the bottom. For highly efficient cooking, plus the advantage of having instant on-off heat, an induction cooktop is another wise new appliance choice, though the newer technology often costs more. And even a new hood that’s more updated or visually interesting can provide a good focal point, says Los Angeles–area designer Christoper Grubb, president of Arch-Interiors Design Group.

▪ Betterlighting can make a huge difference in how much time home owners want to spend in their kitchen and how well it shows to buyers. The best spaces incorporate three essential layers: recessed lighting for an overall effect, with 4-inch rather than 6-inch cans for a less obtrusive look; undercabinet lights to perform tasks, with efficient LEDs or xenon bulbs for quality and energy efficiency; and a decorative fixture or two for mood-making such as pendants, sconces, or a chandelier. Bulbs should depend on manufacturers’ recommendations, but now often are halogens or incandescents. “The decorative choices can add a new design vocabulary to the room,” says San Francisco architect Christian Dauer.

▪ Small 8-inch floor tiles can quickly date a room, as can busy patterns. So replacing them with 16- to 22-inch porcelain floor tiles may make good economic and design sense, as well as decrease maintenance. A bigger budget may permit natural stone. Dauer is keen on wood floors since they’re easy on feet and favors bamboo and cork or a repeat of a wood used elsewhere in the home.

▪ Top on the “get-rid-of list” for many home owners are dark, dated cabinets. But since cabinetry represents 60 percent of many kitchen remodeling budgets, it’s often not possible to replace it totally. Several possibilities exist: Replace the doors or take a less expensive route and repaint them, suggests Kalmus, who also offers some caveats. Be sure the interiors still offer enough room and work well, or else the solution is just a temporary Band-Aid she says, and be sure the paint will cover well since sometimes it won’t if they’re very dark. “Full-overlay doors, for example, usually can be refaced, but the sides may first need sanding and prepping,” Dauer says. For a different punch, Lowell suggests replacing one or two doors in frosted glass within stainless steel frames, while Grubb throws out the idea of removing the fronts completely for a European look. In most cases, new spiffy knobs can make a huge improvement.

▪ For those without sufficient storage— a common complaint of older or poorly arranged kitchens — try finding a closet even if not right in the kitchen but in an adjacent space. The best pantries are equipped with shelves of different heights to arrange a variety of canned goods and with pull-out drawers to make reaching to the back easier.

▪ Because open layouts are high on many buyers’ wish lists, taking down a wall or part of one between a kitchen and adjacent space should be considered if the kitchen is small and closed in and the wall isn’t a load-bearing, supporting one. Be careful that vents aren’t running through it, or be prepared to replace them, Kalmus says. If this isn’t possible, home owners might change out windows or doors for better light, views, and insulation. A new greenhouse-style window can become a spot to grow herbs and small plants.

▪ If home owners have room for an island, but are tight on funds, they might buy a gleaming, stainless-steel, counter-height table from a local restaurant supply store with a shelf underneath, add a few chopping boards from the same supply, and create a professional-looking center they can take with them, says Lowell. This addition also helps free other countertops of clutter.

▪ If the ultimate goal still is to gain a brand new kitchen when dollars permit, a better use of limited funds may be to hire an architect or designer skilled in kitchen planning to draw up a detailed layout that can be bid out later. Many design pros charge a flat fee or hourly rate. Dauer says the price will vary depending on the part of the country, size of the room, wish list, and extent of the remodeling work — if plumbing or HVAC systems need to be changed or walls taken down. His best guess is from $135 on up per hour. Chicago architect Allan J. Grant pegs it at between $90 and $150, depending on the person’s experience, plus reimbursable expenses.

Posted in BoydTeam Blog
May 9, 2019

Stunning Ceilings: The Latest Eye Candy for the 5th Wall

Ceilings are too often the plain Jane element of a listing, but this element of your listing’s structure can assume a starring role and transform a space with minimal effort and expense. Learn about your clients’ options, from millwork to lighting, different shapes, paint, and even wallpaper.

When factory buildings and warehouses in New York’s downtown manufacturing district were converted to loft-style apartments starting in th 1950s, a grittier industrial chic took hold, leaving ceiling ductwork and beams exposed. Lofty heights remained in vogue throughout the 1980s and ’90s, but fancier vaults, peaks, and arches emerged as McMansions became the rage. However, as concern about the high cost of energy consumption gained traction, the idea of heating and cooling all that extra space turned some off high ceilings. They were lowered, though rarely to less than 8 feet, and left unadorned, a nod toward a modern aesthetic that often shunned crown molding and other details.

These days interest in personalizing space has meant ceilings have begun to play a role in helping rooms take on different personas, create memorable impressions on buyers, and solve problems such as adding visual depth to a low room.

Lisa Pickell, president of Orren Pickell Building Group, custom home builders in Chicago, is a fan of maximizing ceilings. “They offer a great opportunity to extend and enhance an aesthetic,” she says. But she also recommends doing so when planning a room’s décor rather than as an afterthought, which can make the project more expensive.

Erin Powell, design director and principal at RoOomy, an online staging firm out of San Jose, Calif., concurs that a well-planned ceiling treatment can help a listing stand out. “It usually won’t make or break a purchase, but it opens up the chance to make a buyer more interested,” she says.

Here are five ways to showcase a ceiling. Use them sparingly—certainly not in every room—to avoid visual confusion. “Otherwise, the concept may lose its specialness,” Pickell says.


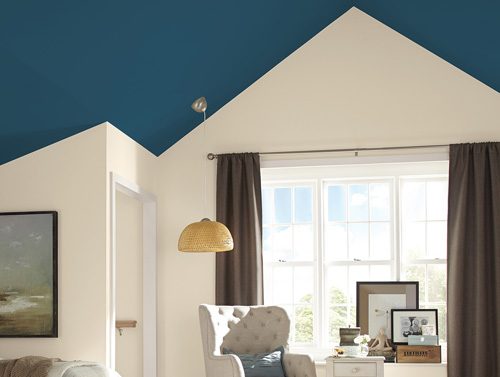
dark blue ceiling

© Sherwin-Williams


Paint

This is the least expensive way to make a ceiling stand out and alter its look without major architectural change. New homes often feature the same white color on walls and ceilings, but broker Matt van Winkle with RE/MAX Northwest in Seattlerecommends painting the ceiling slightly lighter than what’s used on the walls to add depth. Generally, he advises steering clear of bold colors, except in children’s rooms.

Others, however, like adding more color for different visual effects. Designer Rebecca Pogonitz of Go Go Design in Chicago likes to use darker colors to create a cozy, almost a cocoonish, feeling, which she sometimes pairs with white trim to keep the overall feeling from seeming too heavy. Kristie Barnett, founder of The Decorologist in Nashville, also likes dark choices when staging a home for a memorable impression.

Sometimes, a wildly unexpected hue can be the easiest way to update a room, which was the approach architect Anik Pearson took with a vintage New York apartment that had its footprint and bones intact. “We restored it to its glory but with a modern twist by painting the dining room’s walls and beams a bold teal, filling in the space between beams in white, and running some chinoiserie-inspired wallpaper all around,” she says. Bob Zuber, partner, principal, and head of architectural design at Morgante Wilson Architects in Chicago, finds that tinted Venetian plaster warms up ceilings.

For the best coverage and less splatter, Rick Wilson, director of product information at Sherwin-Williams, stresses the importance of using quality ceiling paint. His colleague Sue Wadden, director of color marketing, suggests going with flat or matte finishes to hide imperfections and produce a polished, clean look for any color choice. Otherwise, painting the ceiling is no different from painting walls.


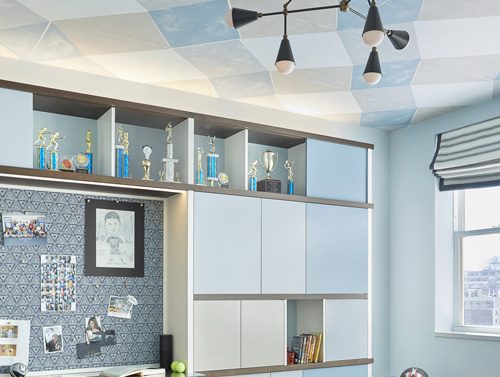
Wallpapered ceiling

© Emily Gilbert


Wallpaper

While many see this option as something of a throwback, wallpaper has found favor among more design professionals of late and for multiple reasons. “A graphic paper can define an activity area in an open-plan space; colorfully patterned papers can pull together a palette in a room, and gold, silver, or pewter leaf paper, which we use often, add stature, drama, and radiance when coupled with the right kind of lighting,” says Chicago-based designer Jessica LaGrange. “Wallpaper can hide cosmetic blemishes or introduce pattern in rooms where all the walls are taken such as a kitchen or family area with copious cabinetry.”

Pogonitz, who likes using bold and detailed patterns on ceilings, says it’s important to do the same prep work as you would for any wall surface—”patch and smooth out the ceiling as needed.”

But many design pros offer caveats with this approach. Powell cautions that wallpapering both a ceiling and walls can look excessive, so she recommends covering one or the other. LaGrange warns against using paper with a definite directional cue, such as those with a clear top and bottom, since it won’t be read “correctly” from a visual standpoint.

Barnett, who trains stagers, suggests avoiding wallpaper on the ceiling when selling. “It’s so taste-specific and many are still scared of paper,” she says. One way to hedge bets is to suggest one of the newer easy-to-remove papers from sources like Chasing Paper.


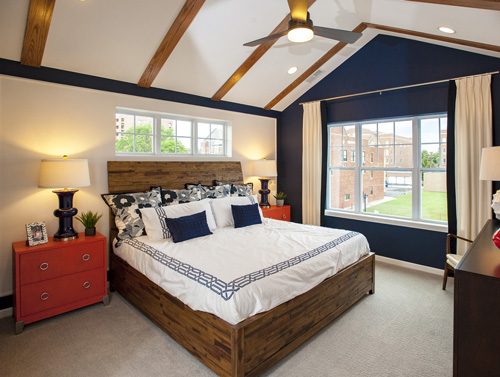
vaulted ceiling

© Lexington Homes


Shape

Ceilings don’t have to be a flat plane, though it’s certainly easier and less costly to make this decision before construction or during a major remodeling and in a one-story space. Van Winkle has found coffered ceiling treatments are attracting a lot of attention these days among consumers. That could mean a pitched, vaulted, or arched shape that rises upward and provides a greater sense of airiness, drama, and light.

Homebuyers who purchase townhomes in communities developed by Chicago-based Lexington Homes are increasingly requesting to upgrade to ceilings with volume, particularly tray designs in master and secondary bedrooms, says sales director Todd Lesher. “Ceiling upgrades are one of the most common selections we encourage buyers to make, as they do not add a lot of cost, but make a big impact,” he says. “Buyers like that the volume helps open up the space and make the rooms seem larger and more expansive.”

Key to adding any volume to a ceiling is carefully considering the relationship of the elements to the size of the room to maintain proper visual scale, says Zuber. “You never put a tall ceiling in a small space or a short ceiling in a large room,” he says.


ceiling with millwork

© Emily Gilbert


Millwork

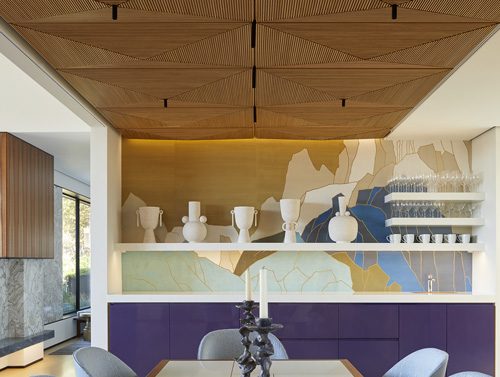
Woodwork is used for all sorts of interior spaces—doors, floors, walls, and the trim detailing that’s used in crown molding at the top by the ceiling. Such architectural trim, especially when wider and thicker, makes a house look more luxurious, says Barnett. It can also be used in more elaborate ways, atop a ceiling in recessed grids for a coffered effect or in one large central portion that’s recessed and higher, in what’s called a tray design. Merritt, in Mentor, Ohio, often designs these complex arrangements of wood in clients’ homes. The company recently fashioned an elaborate grid pattern from American white oak for a large Hamptons, N.Y., home. Haver and Skolnik Architects, in Roxbury, Conn., known for building and renovating traditional homes, frequently uses beams and other millwork to add coziness and an aged character. And Pearson recently used millwork to define an area in an open-plan New York apartment and baffle sound. In an adjacent kitchen, she added trim to bring extra drama to a skylight.

But simpler uses of crown molding or ceiling trim can achieve effects such as unifying adjoining rooms for less than $1,000, says Julie Whitley, director of architecture design at homebuilder Red Seal Development Corp. in Northbrook, Ill. One DIY technique that’s attracted wide attention and adds an updated farmhouse feel is to use shiplap, basically manufactured boards with grooves that fit together snugly. The look picked up steam after celebrity TV couple Chip and Joanna Gaines of HGTV’s “Fixer Upper” show began using them in countless projects, including on ceilings. For a more modern vibe, Zuber of Morgante Wilson Architects recommends trim with an angled or slanted profile rather than straight rectangular boards. He advises keeping millwork in the right proportion to the ceiling’s height. “Four-inch crown is good for an 8- or 9-foot ceiling,” he says.

Whether the millwork is left natural or painted should depend on how much homeowners want it to stand out or complement a certain period or style. Winkle recommends keeping millwork white, which makes it easy to live with over time and appeal more universally, especially to buyers. For traditional homes, however, Powell favors dark hues that more readily reveal texture. But she cautions that going dark can visually bring a ceiling down.


ceiling lights

© RoOomy Virtual Staging


Lighting

Ceiling lights have changed a great deal in recent years; even housings for recessed cans reflect trends with different trim colors, materials, and diameters. Zuber likes placing them strategically around a ceiling rather than peppering a line of cans in the more common shotgun approach. Some also suggest eschewing the expected fixture at the center of a room, particularly in dining and master bedrooms, which gives greater flexibility when arranging furniture, says Amber Shay, national director of design studios for Meritage Homes, a Scottsdale, Ariz., builder of single-family homes.

In general, oversized fixtures are more on trend, along with ceiling fans with lights built in, and almost all bulbs are LEDs for better performance, greater efficiency, and new smart-home applications, says Joe Rey-Barreau, an architect, lighting designer, and education consultant for the American Lighting Association. Among some of the new LED uses are in linear strips that can be installed easily inside or on top of cabinets, in bookshelves, along toe kicks in kitchens and baths, and in ceiling coves and cornices. For sellers who want to update fixtures before listing to improve how rooms show, Rey-Barreau says the number of attractive, affordable options has increased. That’s especially helpful if they must leave such upgrades behind, which of course depends on the sales contract.

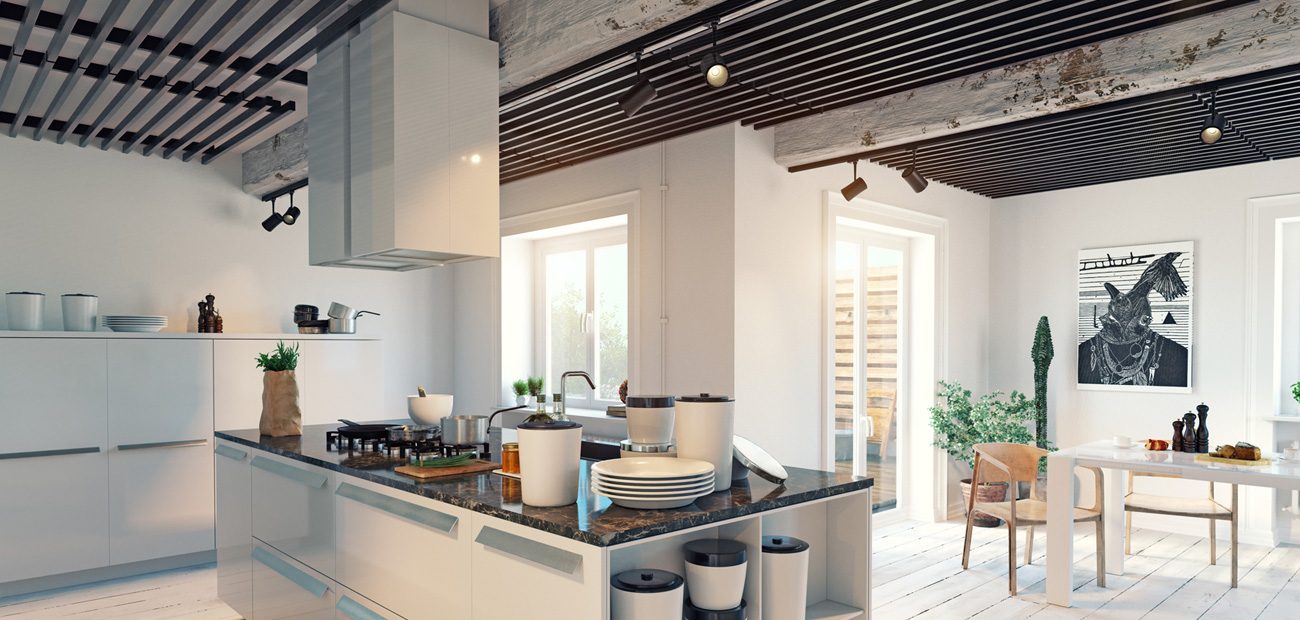
wood kitchen ceiling in loft
Posted in BoydTeam Blog
May 7, 2019

Moving Out: How to Prep and Stage Your Home for Sale When You Have Kids


Photo via Pixabay by StockSnap


Moving Out: How to Prep and Stage Your Home for Sale When You Have Kids


Moving and preparing your home for sale is something many Americans go through at least once in their lives, but there is no guide book to help them figure out how to get started. When you’re a busy parent, it can be overwhelming to try to get everything cleaned and staged and maintain it all ahead of a sale, especially if you have a large home or a lot of belongings that have to be sorted through. Decluttering is an important step in getting a house ready to put on the market, and it can help you stay organized throughout the process.


It’s crucial to create a plan that will help you stay on track while your home is for sale. Staying organized will allow you to keep things clean and neat, and will make the staging process much easier. Keep in mind that staging a home can mean many things, from decluttering to making sure there are no stains or odors lingering, so it’s important to think about what good staging will mean for you. For example, if you have pets, don’t forget to include the yard in your home prep.


Here are a few tips on how to move on and get a quick sale by prepping and staging your home when you’re a busy parent.


Call a pro


Sometimes, when you’re a busy parent, it’s easiest to just find a pro to get the work done rather than attempting to do it yourself. This applies to everything from making dinner to cleaning the house, and when your home is on the market, it’s important to make that call if the job is too overwhelming. A professional cleaning service can make a huge difference in the presentation of your home and can free up quite a bit of your time, so if the money is in the budget, don’t hesitate to lay it out. Keep in mind that the average cost of a one-time cleaning service in Myrtle Beach is between $85 and $191.


Make it smell fresh


One of the easiest ways to boost the appeal of your home is to remove stains and odors. By making each room smell great, you can ensure that potential buyers associate your home with positive feelings. Our sense of smell is closely tied to memory, which means most people react favorably to a space that has a nice scent. Freshly-baked cookies, vanilla, and cinnamon are warm scents that tend to draw people in. Also make sure you deodorize and air out spaces that have had pets in them; you can use a mixture of hot water and vinegar to clean most pet stains.


Remove clutter


The word “clutter” means something different to everyone; for some, it’s excess items that can be thrown away or donated, but for others, it’s anything that is unnecessary to a given space. You might look at your floor-to-ceiling bookshelf full of books and see nothing wrong, but a potential buyer might be overwhelmed by it. Think about packing up collections to put into storage until the move, and clean off all surfaces as thoroughly as possible. Get the things you need to hold onto for the moment--such as toiletries and pots and pans--organized with storage solutions that will make it easy to store your items at a moment’s notice.


Hold a yard sale


Before you put your home on the market, consider having a yard sale. It can help you get rid of items you no longer need or want while generating some extra cash for the move at the same time. Price the items before you set them out, and leave some room for haggling. Place something shiny or sparkly at the front of your spread to attract attention, and donate anything you don’t sell. This will help you clear out clutter from an overpacked basement, attic, or crawlspace.


Moving, preparing, planning, cleaning, and staging--they’re big jobs, and when you have a home sale riding on them, it can be stressful. Get help from your realtor and from friends and family when you need it in order to stay on track and keep anxiety at bay. With a good plan, you can get it all done in no time.


Source:  Courtesy of Kristin Louis

Posted in BoydTeam Blog
May 7, 2019

16 Ways to Make Money From Home

The reasons that people want to make money from home are as unique as their individual circumstances. Some just want to pick up a little extra cash to supplement their income. Others are really looking for a lifestyle change—to simplify work-life balance or eliminated wasted time commuting.

Given the range of skills and experience people have, the best way to make money from home varies wildly. The following list of 17 different ways to bring in money from the comfort of your home has a little something for everyone.

One of these has got to be right for you! 


    • 01

       Direct Sales

      Direct Sales party
      Getty/Steve Debenport


      This is the classic work-at-home mom gig, but it's for a lot more people than just moms! Selling stuff you love can be a great way to make extra money from home, even if you work in an office most of the day. Direct selling is scalable to your own lifestyle, ambition, and talents. You can keep it casual and mostly sell to friends and acquaintances. Or, if you really get to networking online and in person, you can build a client base outside your existing circles.

      Direct selling is structured as multilevel marketing. This means you can also build a revenue stream by recruiting other salespeople. Just be careful of pyramid schemes, which work the same way.


    • 02

       Search Evaluation

      Google Search
      Iain Masterton/Getty Images


      Search evaluators are the human checkers on search engines’ algorithms that come up when you type in a search term. Following very specific guidelines, they provide feedback to make sure results are accurate, complete, relevant and current.

      To become a search evaluator you need to be an expert in language and the culture. Often search evaluation jobs are bilingual positions, but there are some opening for English-only search evaluators. A college degree is often required.


    • 03

       Rent Out a Room in Your Home

      Elegant bedroom
      Hero Images / Getty Images


      Use your home to work from home. If you live in an area where there is a demand for short-term rentals (like near a university or the downtown of a large city), you may well be able to find renters by networking in your community. However, with the rise of Airbnb and places like it the Internet has once again made it much easier to make money from home. Using these sites you can rent out a private room, shared room or even your whole house for a night or month or whatever period of time you like. 


  • 04

     Drive Your Car

    Young woman driving car
    Tetra Images / Getty Images


    Like Airbnb, becoming a ridesharing driver for companies like Uber, Lyft or Sidecar is a way to join the shared economy. And though it is not technically earning money from home,  it allows the same kind of flexibility and it is a way to use an asset you already own (i.e. your car) to make money. There are things to keep in mind, though, about driving other people such as whether your car insurance will cover you and how you pay taxes on your earnings. 


  • 05

     Get Your Boss to Let You Telecommute

    Online Tutor Video Call Telecommute
    Chad Springer/Getty Images


    To get started making money from home, one of the more obvious places to look is at your current job. When companies allow telecommuting it is most often a perk for existing employees.

    To turn your current job into a telecommuting one, the first thing you need to do is to develop a telecommuting proposal for your supervisor. However,​ before you do that consider how your job might (or might not) work as a telecommuting position.


  • 06

     Website and App Testing

    Website testing
    Daniel Sambraus / EyeEm/Getty Images


    Companies need people with all different levels of technical ability to test out their websites, apps and social media offerings. Sign up with one of these website usability testing companies and take on quick jobs surfing the web and playing with new apps. It’s not a career, but it is an easy way to make extra money from home. The only thing to keep in mind is that this won't likely be a steady gig, just occasional.  Learn more about website testing.​​


  • 07

     Call Center Agent

    Close up portrait of smiling businesswoman with headset
    Sam Edwards / Getty Images


    Working at a virtual call center is a good way to start a new career from home. Unlike in a lot of other industries, home call center companies hire new employees (often without a lot of experience) to work remotely. Agents might work in customer service, sales or technical support.


  • 08

     Chat Agent

    Cape Verdean woman typing on keyboard
    Blend Images/GI/Jamie Grill / Getty Images


    If talking on the phone is not practical for you, you can still work a customer service job from home. Many of the same companies that hire call center agents, also hire chat agents. And in addition to these customer service chat jobs, there are otheronline chat jobs from home. These include answering questions, doing internet research, moderating in social media and more. 


  • 09

     Start Your Own Home Day Care

    Childcare
    The Image Bank/Getty Images


    If you love children and want a career in childcare from your home, then a home daycare center could be right for you. Starting a home daycare center, like any home business, takes a lot of work, research, start-up costs and networking to get it going. Every state has different regulations, which could require physical improvements to your home. Learn more about starting a home daycare.

    Another route to make money in childcare is to simply babysit for families you know. However, this would usually require going to other people's homes. 


  • 10

     Pet Care Business

    Dog Walker
    Getty/your personal camera obscura


    There are a lot of services that people will purchase for their pets. While most of the time, running a pet-services business won't be directly from your home, they offer the same kinds of lifestyle flexibility as a home business. Some pet businesses include:

    • Open a Doggie Daycare
    • Become a Dog Walker
    • Work as a Dog Trainer
    • Start a Mobile Pet Grooming Business
    • House/Pet Sitting


  • 11

     Type From Home

    Type from home
    Ezra Bailey/Getty Images


    If you're a fast typist there are many ways to make money from home by typing. Some you need experience and training others you don't. Data entry, for instance, takes very little experience; however, if you aren't fast enough you won't make any money at. Specialty transcription work (like medical) may require a degree and experience to get started.


  • 12

     Become a Writer

    Writer
    Portra Images / Getty Images


    Want to do more than type words but instead create? Consider a career in writing. There are so many ways to be a writer (think blogging,  fiction writing, and children’s books), and most of them can be done from home either as a telecommuter and a freelancer. The great thing about writing is you can start small with very little experience. You won't make a lot at first but as you build your portfolio you can expand into more lucrative types of writing.


  • 13

     Pick Up Small Jobs

    Supermarket price check
    VOISIN / Getty Images


    If you have skills that are in demand, you can always pick up odd jobs around your neighborhood, networking in the real world to find real-world jobs. But don't stop there! There are now so many ways to use the Internet to find small jobs. Short task sites offer diverse ways to find skilled and unskilled jobs both online and in the real world--shopping and performing price checks, cleaning, repairs, writing, editing, translation, transcription, data entry, website usability testing, social media tasks, surveys, and online research. 


  • 14

     Sell Your Handiwork

    Sell arts and crafts
    Howard Grey / Getty Images


    Take the hobby you love and do it for money...from home. The number of possible types of crafts you could make is endless--knitting, jewelry, scrapbook, pottery, ornaments, textiles and so on. To make this work, though, you have to not only create a quality product but you need to know how to market it. You can go the old-fashioned route and take your wares to craft shows and flea markets or use the Internet to expand your options. With online options like Etsy and eBay, your potential market is worldwide, but so is your competition. 


  • 15

     Go Shopping

    Shopping
    Getty/Mint Images


    There are few ways to make money while you shop. You can pick up short tasks that involve shopping, like doing price checks or photographing in stores or you can go mystery shopping. Mystery shopping is definitely a real way to make money but you have to be careful because the jobs can be the bait for scams, so you have to know the signs of mystery shopping scams. But there are legitimate companies that hire mystery shoppers. 


  • 16

     Become a Tutor

    Education jobs
    Michal Szwedo/Getty Images


     Tutoring can be done in-home or online. The in-home tutoring will take networking and teaching experience to build your business. Online tutoring, however, can be done through companies that connect tutors with students while providing the needed infrastructure (i.e. web conferencing services) for a cut of the fees. Most require a college degree and teaching experience but for some those requirements may be negotiable.

Posted in BoydTeam Blog
May 1, 2019

Making Financial Decisions After A Family Death

Three Big Financial Decisions You’ll Need to Make After a Death in the Family

When imagining the death of a spouse or other close family member, you think about how hard it will be to live without them and how best to honor their memory. What most people don’t think about is how a death in the family affects their finances. But you should.


Death is a financial matter as much as it is an emotional one. Not only must surviving family wrap up their loved one’s estate, they also face big bills and big decisions about their financial future.

How to Handle Medical Bills

Depending on the nature of your loved one’s passing, they may have left behind substantial medical debt. If the deceased’s estate is large enough, the estate pays outstanding debts before distributing assets to beneficiaries. If the debt is larger than the estate, you’re not responsible for outstanding debts unless the deceased was your spouse and you live in a community property state. If a creditor is contacting you about debts you’re not responsible for, the Federal Trade Commission explains how to stop it.

How to Pay for a Funeral

The cost of a burial and funeral takes many families by surprise. A traditional funeral runs $7,000-$10,000. If you’re not prepared for the expense, you may discover you can’t afford the send-off your loved one deserves.


This is why it’s so important to discuss funeral plans while alive, including what type of funeral you want and how to fund it. Funeral costs are commonly paid out of life insurance policies or less expensive burial insurance policies. Sometimes called final expense insurance, burial insurance provides small sums to cover funeral costs. In some cases, the death benefit is high enough to get rid of outstanding debts as well.


If your loved one died without money for a funeral, consider cremation, which is significantly cheaper than a traditional burial.

What to Do with the House

If the deceased was a breadwinner in your household, you may realize you can no longer afford your home. Moving in the wake of a loss is scary: Not only do you have to sell your house and buy a new one in your budget, you also have to pack up a lifetime of memories and start over in a new place.


Moving is stressful, but it has its benefits too. You’ll gain long-term financial security by buying a home you can afford and the opportunity to move closer to your support system.


It’s hard to stay organized and make little decisions while grieving, so finding a great real estate agent is crucial for home buying and selling. Your agent will help you understand your goals for the move and find the right home, as well as sell your old home quickly so you’re not stuck in financial limbo.


The hardest part of moving will be sorting through your loved one’s things. Hire packing help for general household goods so you can focus on this emotionally-demanding task. Get rid of the obvious things first, like half-used cosmetics and old mail. Aim to pare clothing, books, and other collections down to select favorites, but don’t push it if you’re struggling to let go. You can revisit the task when you’ve had more time to heal.


While you shouldn’t rush into big decisions after the death of a loved one, you can’t afford to wait too long to take action. Take a good look at your financial status after your family member’s passing. By assessing where you stand and where you need to end up, you can start planning the steps to secure your financial future.


Image via Pexels

Posted in BoydTeam Blog
April 30, 2019

Investing for Beginners

Beginner's Investing Guide to Make Your Money Work for You


So you've decided to start investing. Congratulations! Whether you're just starting out on your own, in the middle of your career, approaching retirement age, or in the midst of your golden years, this means you've begun to think about your financial future, and how you might prudently manage your capital so that it can work for you.

Nobody starts out an expert, and even the best investors in the world were once sitting where you are.

Let's start with two basic questions:

  1. Where should you begin?
  2. How do you begin?

Those two inquiries might seem daunting, especially if you've encountered the array of intimidating investing terms — like price to earnings ratio (p/e ratio), market capitalization, and return on equity. But getting started with investing isn't as scary as it might seem.

The First Investing Step Is Figuring Out Which Types of Assets You Want to Own

Let's start with this basic truth: At its core, investing is about laying out money today with the expectation of getting more money back in the future — which, accounting for timeadjusting for risk, and factoring in inflation, results in a satisfactory compound annual growth rate, particularly as compared to standards considered a "good" investment.

That's really it; the heart of the matter. You lay out cash or assets now, in the hope of more cash or assets returning to you tomorrow, or next year, or next decade.

Most of the time, this is best achieved through the acquisition of productive assets.

Productive assets are investments that internally throw off surplus money from some sort of activity. For example, if you buy a painting, it isn't a productive asset. One hundred years from now, you'll still only own the painting, which may or may not be worth more or less money. (You might, however, be able to convert it into a quasi-productive asset by opening a museum and charging admission to see it.) On the other hand, if you buy an apartment building, you'll not only have the building, but all of the cash it produces from rent and service income over that century. Even if the building were destroyed after a decade, you still have the cash flow from ten years of operation — which you could have used to support your lifestyle, given to charity, or reinvested into other opportunities.

Each type of productive asset has its own pros and cons, unique quirks, legal traditions, tax rules, and other relevant details. Broadly speaking, investments in productive assets can be divided into a handful of major categories. Let's walk through the three most common kinds of investments: Stocks, bonds, and real estate.

Investing in Stocks

When people talk about investing in stocks, they usually mean investing in common stock, which is another way to describe business ownership, or business equity. When you own equity in a business, you are entitled to a share of the profit or losses generated by that company's operating activity. On an aggregate basis, equities have historically been the most rewarding asset class for investors seeking to build wealth over time without using large amounts of leverage.

At the risk of oversimplifying, I like to think of business equity investments as coming in one of two flavors — privately held and publicly traded.

Investing in Privately Held Businesses: These are businesses that have no public market for their shares.

When started from scratch, they can be a high-risk, high-reward proposition for the entrepreneur. You come up with an idea, you establish a business, you run that business so your expenses are less than your revenues, and you grow it over time, making sure you are not only being well-compensated for your time but that your capital, too, is being fairly treated by enjoying a good return in excess of what you could earn from a passive investment. Though entrepreneurship is not easy, owning a good business can put food on your table, send your children to college, pay for your medical expenses, and allow you to retire in comfort.

Investing in Publicly Traded Businesses: Private businesses sometimes sell part of themselves to outside investors, in a process known as an Initial Public Offering, or IPO. When this happens, anyone can buy shares and become an owner.

The types of publicly traded stocks you own may differ based on a number of factors. For example, if you are the type of person that likes companies that are stable and gush cash flow for owners, you are probably going to be drawn to blue-chip stocks, and may even have an affinity for dividend investingdividend growth investing, and value investing.

On the other hand, if you prefer a more aggressive portfolio allocation methodology, you might be drawn to investing in the stock of bad companies, because even a small increase in profitability could lead to a disproportionately large jump in the market price of the stock.

Investing in Fixed-Income Securities (Bonds)

When you buy a fixed income security, you are really lending money to the bond issuer in exchange for interest income. There are a myriad of ways you can do it, from buying certificates of deposit and money markets to investing in corporate bondstax-free municipal bonds, and U.S. savings bonds.

As with stocks, many fixed-income securities are purchased through a brokerage account. Selecting your broker will require you to choose between either a discount or full-service model. When opening a new brokerage account, the minimum investment can vary, usually ranging from $500 to $1,000; often even lower for IRAs, or education accounts. Alternatively, you can work with a registered investment advisor or asset management company that operates on a fiduciary basis.

Investing in Real Estate

Real estate investing is nearly as old as mankind itself. There are several ways to make money investing in real estate, but it typically comes down to either developing something and selling it for a profit, or owning something and letting others use it in exchange for rent or lease payments. For a lot of investors, real estate has been a path to wealth because it more easily lends itself to using leverage. This can be bad if the investment turns out to be a poor one, but, applied to the right investment, at the right price, and on the right terms, it can allow someone without a lot of net worth to rapidly accumulate resources, controlling a far larger asset base than he or she could otherwise afford.

Something that might be confusing for new investors is that real estate can also be traded like a stock. Usually, this happens through a corporation that qualifies as a real estate investment trust, or REIT. For example, you can invest in hotel REITs and collect your share of the revenue from guests checking into the hotels and resorts that make up the company's portfolio. There are many different kinds of REITs; apartment complex REITs, office building REITs, storage unit REITs, REITs that specialize in senior housing, and even parking garage REITs.

The Next Investing Step Is to Decide How You Want to Own Those Assets

Once you've settled on the asset class you want to own, your next step is to decide how you are going to own it. To better understand this point, let's look at business equity. If you decide you want a stake in a publicly traded business, do you want to own the shares outright, or through a pooled structure?

Outright Ownership: If you opt for outright ownership, you are going to be buying shares of individual companies directly. To do this right requires a certain level of knowledge.

To invest in stocks, think of them as you might your privately held businesses, and remember there are three ways you can make money investing in a stock. Plainly, this means focusing on the price you are paying relative to the risk-adjusted cash flows the asset is generating. Discover how to calculate enterprise value, calculate the gross profit margin and operating profit margin, and compare them to other business in the same sector or industry. Read the income statement and balance sheet. Look at the asset management companies, which hold large stakes, to figure out the types of co-owners with which you are dealing.

Pooled Ownership: An enormous percentage of ordinary investors do not invest in stocks directly but, instead, do it through a pooled mechanism, such as a mutual fund or an exchange-traded fund (ETF). You mix your money with other people and buy ownership in a number of companies through a shared structure or entity.

These pooled mechanisms can take many forms. Some wealthy investors invest in hedge funds, but most individual investors will opt for vehicles like exchange-traded funds and index funds, which make it possible to buy diversified portfolios at much cheaper rates than they could have afforded on their own. The downside is a near total loss of control. If you invest in an ETF or mutual fund, you are along for the ride, outsourcing your decisions to a small group of people with the power to change your allocation.

The Third Investing Step Is Deciding Where You Want to Hold Those Assets

After you've decided the way you want to acquire your investment assets, your next decision regards where those investments will be held. This decision can have a major impact on how your investments are taxed, so it's not a decision to be made lightly. Your choices include taxable brokerage accounts, Traditional IRAsRoth IRAsSimple IRAs, SEP-IRA, and maybe even family limited partnerships (which can have some estate tax and gift tax planning benefits if implemented correctly).

Let's briefly look at some of the broad categories.

Taxable Accounts: If you opt for a taxable account, such as a brokerage account, you will pay taxes along the way, but your money is not nearly as restricted. You can spend it however you want, at any time. You can cash it all in and buy a beach house. You can add as much as you desire to it each year, without limit. It is the ultimate in flexibility but you have to give Uncle Sam his cut.

Tax Shelters: Retirement plans like 401(k)s or Roth IRAs offer numerous tax benefits. Some are tax-deferred, which (usually) means you get a tax deduction at the time you deposit the capital into the account, and then pay taxes in the future, allowing you year after year of tax-deferred growth. Others are tax-free, meaning you fund them with after-tax dollars (read: you don't get a tax deduction), but you'll never pay taxes on either the investment profits generated within the account nor on the money once you withdraw it later in life. Good tax planning, especially early in your career, can mean a lot of extra wealth down the road as the benefits compound upon themselves.

Some retirement plans and accounts also have asset protection benefits. For instance, some have unlimited bankruptcy protection, meaning that if you suffer a medical disaster or some other event that wipes out your personal balance sheet and forces you to declare bankruptcy, your retirement savings will be out of the reach of creditors. Others have limitations on the asset protection afforded to them, but still reach into the seven-figures.

Trusts or Other Asset Protection Mechanisms: Another way to hold your investments is through entities or structures such as trust funds. There are some major planning and asset protection benefits of using these special ownership methods, especially if you want to restrict how your capital is used in some way. And if you have a lot of operating assets or real estate investments, you may want to speak to your attorney about setting up a holding company.

An Example of How a New Investor Might Start Investing

With the framework out of the way, let's look at how a new investor might actually start investing.

First, assuming you're not self-employed, the best course of action is probably going to be to sign up for a 401(k)403(b), or other employer-sponsored retirement plans as quickly as possible. Most employers offer some sort of matching money up to a certain limit. For example, if your employer offers a 100 percent match on the first 3 percent of salary, and you earn $50,000 per year, that means on the first $1,500 you have withheld from your paycheck and put into your retirement account, your employer will deposit into your retirement account an additional $1,500 in tax-free money.

Whether or not your employer offers matching, though, you'll need to invest the money you put in the account. Your 401(k) will probably have a default option, but choose the mutual funds or other investment vehicles that make the most sense for your future needs. As money gets automatically added to your account with each paycheck, it will be put toward that investment.

Next, assuming you fall under the income limit eligibility requirements, you'll probably want to fund a Roth IRA up to the maximum contribution limits permissible. That is $5,500 for someone who is younger than 50 years old, and $6,500 for someone who is older than 50 years old ($5,500 base contribution + $1,000 catch-up contribution). If you are married, in most cases, you can each fund your own Roth IRA. Just make sure you invest the money you put in there — by default, IRA providers will park your money in a safe, low-return vehicle like a money market fund until you direct them otherwise, so decide on which mutual funds, ETFs, or other investments you want to put your money toward.

Once you've taken care of such personal finance essentials as funding an emergency fund and paying off debt, you'd want to return to your 401(k) and fund the remainder (beyond the matching limit you already funded) to whatever overall limit you are allowed to take advantage of that year. With that done, you might begin to add taxable investments to your brokerage accounts, perhaps participate in direct stock purchase plans, acquire real estate, and fund other opportunities.

Done correctly over a long career and with the investments managed prudently, it could increase your odds of retiring comfortably drastically.

Posted in BoydTeam Blog