CATCH THE WAVE

Myrtle Beach Real Estate

We Specialize in Myrtle Beach, SC Real Estate. Lots of options are waiting for you in Myrtle Beach, South Carolina and choosing the right realtors can help you in finding the perfect area and the right home for you and your family and make your dream a reality!  Let us help you in making one of the biggest, if not the biggest, decisions in your life.   

We were both born and raised along the Grand Strand and know the entire Horry County, so no matter what style of home you are looking for or what area you prefer, we can help you!  Please give us a call and let us help you make your dream a reality!  843-222-8566.

Eddie & Julie Boyd - The Boyd Team - Realtors

Myrtle Beach Real Estate - INNOVATE Real Estate


April 29, 2019

How to Remove Inquiries From Your Credit Report

Woman frustrated reading financial documents

Certain businesses check your credit report when you make an application for services with them. Reviewing your credit report allows these businesses to determine whether you qualify for the type of account you're applying for. Credit card companies, lenders, utility companies, and insurance companies are just a few of the businesses that routinely check credit reports as part of their application process.

The credit bureaus keep a record of all the businesses that request your credit report. This record is listed in a section of your credit report called Inquiries. All the inquiries made to your credit report within the last 24 months are listed on your credit report.

Whenever you check your credit report, you're able to see inquiries from businesses that checked your credit after you initiated an application (hard inquiries) and from businesses that check your credit to prescreen you for products and services (soft inquiries). So it may look like you have a lot of inquiries on your credit report. When other businesses check your credit, they only see the inquiries stemming from applications you've made. Businesses don't see soft inquiries.

About Credit Report Inquiries

You may already know that inquiries are a factor in your credit score. Ten percent of your credit score is based on inquiries made for your credit report. Fortunately, not all the inquiries you see on your credit report are factored into your credit score. First, only hard inquiries — those resulting from your applications for credit — are included in your credit score. Second, while inquiries appear on your credit report for two years, only those made within the past 12 months are included in your credit score.

Spacing out your credit applications can keep your credit score from suffering after multiple applications.

Inquiries — specifically hard inquiries — are one of the ways creditors and lenders decide whether to approve a new application. Since inquiries indicate whether you've been shopping for credit recently, potential creditors can attempt to predict whether you've recently taken on accounts that will make it harder to afford the credit card or loan you're applying for. Consumers who've shopped for credit within the past 12 months are generally riskier borrowers than those who have not. This is why the credit scoring calculation factors in inquiries made within the past year.

Note that if you've been shopping for a mortgage or auto loan, your credit report may contain several inquiries from companies you don't recognize. That's because many brokers and car salesmen "rate shop" on your behalf trying to find the lender who will give you the best rate. In that case, several different lenders will pull your credit report in a short period of time to qualify you for the loan.

The good news about rate shopping is that credit scoring models will treat the multiple inquiries as just a single inquiry as long as the rate shopping was done within a specific window of time, ranging from 14 to 45 days depending on the credit scoring model. More recent credit scoring models use a 45-day window. Unfortunately, consumers don't have control over the credit scoring models that lenders use. It's possible that your preferred lender will use a model that uses a 14-day window. For that reason, it's important to keep your rate shopping to as short a period of time as possible.

Steps to Remove Inquiries From Your Credit Report

It's important to check your credit report periodically to make sure there aren't any errors in your report. Errors can be costly to your credit score. In the case of inquiries, they could also reveal potential identity theft.

If you're ​in the market for a new credit card or loan or you're just seeking to clean up your credit, removing unauthorized inquiries is an important step. You want your credit report to be an accurate representation of your credit history.

Federal law gives you the right to dispute inaccurate information from your credit report. This includes hard inquiries you didn't authorize. To dispute an inquiry, write to the credit bureau letting them know the inquiry is an error and ask the credit bureau to remove the inquiry from your credit report. In your dispute letter, reference the name of the business that made the inquiry the date of the inquiry. Including this information will help the credit bureau identify the specific inquiry you're disputing.

Once the credit bureau receives your dispute, they're required to do an investigation with the company that listed the inquiry on your credit report. If the investigation shows the inquiry in indeed an error, the inquiry will be removed from your credit report.

Don't be surprised if you don't see a significant improvement in your credit score after having inquiries removed. Inquiries make up only a small part of your credit score. You'll see the best improvement in your credit by focusing on more significantly negative information like late payments or high credit card balances.

Inquiries Resulting From Fraud

Use the credit report dispute process to remove fraudulent inquiries from your credit report. Also review the rest of your credit report carefully for any unauthorized accounts. Consider placing a fraud alert or security freeze on your credit report to prevent future unauthorized inquiries and the opening of fraudulent accounts.

What About Inquiries You Actually Made?

Trying to remove an inquiry that resulted from an application you actually made is next to impossible. Credit bureaus have a right to report accurate information as long as it's complete and within the credit reporting time limit (two years for credit report inquiries). Therefore, you can't remove inquiries from your credit report because you changed your mind or you don't like having the inquiry there.

Fortunately, inquiries are not a big cause for concern. They're only on your credit report for a short period of time and only affect your credit for an even shorter period of time. An inquiry made this month will factor out of your credit score next year this time.

How Many Inquiries Are Too Many?


Unfortunately, it's impossible to know the exact number of inquiries that will hurt your credit score or your ability to get approved for a loan. The best way to keep your inquiries under control is to minimize the number of credit-based applications you make, especially within a 12-month timeframe.

Posted in BoydTeam Blog
April 29, 2019

North Myrtle Beach Giant Inflatable Water Park

This Giant Inflatable Water Park In North Myrtle Beach South Carolina Proves There’s Still A Kid In All Of Us

Water activities abound in the Palmetto State. From beaches to lakes and waterfall swimming holes, you’re never far from your next opportunity to pop in the water to cool off and have some fun! One of the largest floating aqua parks on the east coast is right here in our own front yard and it’s sure to make you feel like a kid again.

The Aqua Park at Shark Wake Park opened in 2016. Have you been yet? We’d love to hear about your experience!

Shark Wake Park and the Aqua Park are located at the North Myrtle Beach Sports Complex. The address is 150 Citizens Cir., Little River, SC 29566. According to the calendar on the website, the Aqua Park opens Memorial Day Weekend. Book your time at the park in advance at this link on the official website. The cost for 45 minutes is $25/person. An additional 45-minute session (on the same day) can be added for $10/person. Want an all-day pass? That’s $50/person. Learn more on the official website – and get ready for some awesome fun in the sun!

Posted in BoydTeam Blog
April 26, 2019

What You Need to Know About Credit Repair

Know These 9 Critical Facts About Mending Your Credit

Woman reviewing her credit report

It's difficult to navigate today's society with a bad credit. A number of companies use your credit to decide whether to do business with you and to set the pricing for products and services you use.

Consumers with a troubled credit history often seek credit repair to improve their credit to have an easier time financially. As you navigate credit repair and evaluate the best option for your credit, here are the most critical things to know about credit repair.

1. You can do it yourself.

Many people think they have to hire a professional credit repair company to help repair their credit. While a reputable credit repair company may be an option for some people, there's nothing a credit repair company can do for you that you can't do for yourself. There's plenty of information available in books and on the internet that you can use to educate yourself on how credit works and what you can do to repair your own credit.

Removing negative information, for example, can be done with techniques like credit report disputes, debt validation, pay for delete, and goodwill letters. Many of these are the same strategies credit repair companies use to get negative information removed from your credit report. Doing it yourself not only saves you money but also gives you power and control over your own credit history. Once you know the credit repair tactics, you can use them anytime in the future if it becomes necessary.

2. Credit repair is about your credit report, not your credit score.

When you're repairing your credit, you may watch for your credit score to go up. But credit repair is about improving the information on your credit report. This is what ultimately influences whether you have good credit or bad credit and is the basis of your credit score.

Checking your credit report is the first thing you should do when you're ready to start working on your credit so you can see the information that's hurting your credit. You can get a free copy of your credit report once a year from each of the major credit bureaus — Equifax, Experian, and TransUnion — by visiting www.annualcreditreport.com.

3. Your credit score helps you see where your credit stands.

Whether you have good or bad credit is based on the information in your credit report. However, it's difficult to look at your credit report and tell whether your credit is good or bad. That's why watching your credit score is useful in credit repair. A low credit score indicates a poor credit history that needs work. As your credit score improves, it's an indication that your credit history is improving.

Your credit score is based on five categories of information: payment history, amount of debt, the age of credit history, types of credit accounts, and recent applications for credit. Improving your credit in each of these areas will boost your credit score.

Purchasing your credit score each time you want to see where you stand can get expensive. Using a free credit score service like Credit Karma or Credit Sesame will allow you to monitor your credit progress at no cost. When you're signing up for a credit monitoring service, look for one that doesn't ask for a credit card. Otherwise, there's a chance you may be actually signing up for a free trial subscription that will begin charging you each month if you don't cancel the services.

4. Removing accurate negative information is tough.

Note the emphasis on accurate. Credit bureaus are only legally obligated to remove inaccurately reported information from your credit report. It doesn't matter whether those inaccuracies are positive or negative. It's the fact the information is inaccurate that allows you to remove it from your credit report, not that it's negative.

When accurately reported negative information hurts your credit, it's tougher to remove this information because the credit bureaus are within their rights to report this information. In fact, the integrity of the credit system depends on credit bureaus reporting all accurate information, even information that's negative.

There are some strategies to remove accurate negative information — like a collection account for a debt you legitimately owe. These strategies may take more time and effort than a simple credit report dispute. For these types of accounts debt validation (for collection agencies), pay for delete, and goodwill deletion requests are the best options.

5. Doing nothing might be a strategy.

Negative information won't stay on your credit report forever. Most negative information will only stay on your credit report for seven years. There are a few exceptions. Chapter 7 bankruptcy and unpaid tax liens can stay on your credit report for up to 10 years. Unpaid judgments can remain on your credit report through the state's statute of limitations for that type of debt if the statute is more than seven years.

If an account is nearing the credit reporting time limit, waiting for it to fall off may be less stressful and time-consuming than trying to remove the account with dispute letters or similar strategies.

Contrary to popular belief, taking action on a negative account does not extend the credit reporting time limit. So, if you pay off a six-year-old debt collection, for example, it will still drop off your credit report after year seven. Some newer versions of the FICO and VantageScore do not include paid collections in your credit score.

6. Closing accounts won't help.

There's a widespread belief that only open accounts are included in a person's credit report, that closing an account will remove it from their credit report. Sorry to disappoint you if you were hoping that you can save your credit by closing an account that's giving you problems. In some cases, closing an account can actually hurt your credit score.

Closing an account won't remove it from your credit report. All the details about the closed account will continue to be listed on your credit report as reported by your creditors.

"Before [closing accounts], consumers should take into consideration other factors that comprise credit scores, such as the length of time the account has been opened," says Nancy Bistritz, Director Public Relations and Communications of Global Consumer Solutions at Equifax, one of the three major credit bureaus. "If you've exhibited the right kinds of behavior for an established period of time with an account (i.e., paying on time every time), then closing that account may not make sense."

If the account is in good standing or can be brought back into good standing by catching up on the past due balance, leaving the account open can actually help you repair your credit. You'll need open, active accounts with a positive payment history to improve your credit score. Opening new accounts with a bad credit score can be difficult so rehabilitating the accounts you already have open can be much easier.

7. Credit repair companies are often untrustworthy.

Credit repair companies do a great job of promoting their services to vulnerable consumers who want better credit but also do not completely understand how credit works or how much influence they have over their own credit scores.

Many credit repair companies make lofty promises — often promises they can't fulfill — charge upfront fees and fail to deliver on their services. All these are prohibited by Federal law, but consumers who are unfamiliar with the law wouldn't realize they were being taken advantage of until it's too late.

Over the past several years, the Federal Trade Commission has pursued dozens of credit repair companies who have broken the law. These companies are often required to pay hefty fines and in some cases are banned from doing business in the credit repair industry.

A few signs you're dealing with a shady credit repair company: they ask you pay upfront before any services begin, cite an affiliation with the government or special relationship with the credit bureaus, promise a specific credit score, promise to delete accurate information from your credit report, fail to inform you of your right to dispute information directly with the credit bureaus, or ask you to waive your rights under the Credit Repair Organizations Act.

8. You can't expect overnight results.

It takes time to rebuild a bad credit history. Your credit score considers your most recent credit history more significantly than older items. A good credit history typically has a minimal number of negative entries and lots of recent positive credit information. A few months of on-time payments is a step in the right direction, but it won't give you excellent credit right away. As time passes and the negative information falls off or gets older, and you replace it with positive information, you'll see your credit gradually improve.

Repairing bad credit takes time, so it's important to be patient with the process. The amount of time it takes can vary from person to person depending on the information on your credit report and how you're going about credit repair. You might see immediate boosts when something is deleted from your credit report.

Furthermore, your credit score may fluctuate during the credit repair process as the information in your credit report changes. Don't be alarmed by drops in your credit score. Focus on the general trend of your credit score over a period of time rather than the daily fluctuations.

9. Your improved credit won't last if you don't change your habits.

Many people go through credit repair — whether doing it themselves or hiring a company — so they can borrow money, for a mortgage or auto loan, for example. There's nothing wrong with this. Many people, unfortunately, find themselves back in the same situation because they don't borrow responsibly, ending up with more debt than they can handle and slip back into habits of missing payments.

If you want your good credit to last, you have to adopt habits that will maintain good credit. This means borrowing only what you can realistically afford to pay back (and maybe even a little less). Paying your bills on time is perhaps one of the best things you can do for your credit.


Nancy Bistritz says, "When it comes to creditworthiness, a great rule of thumb to remember is to pay your bills on time every time. Lenders and creditors want to know that you've been able to satisfy your financial commitments on time every time. Therefore, paying bills on time is an important, fundamental behavior to establish early on."

Posted in BoydTeam Blog
April 25, 2019

I Don't Need a Real Estate Agent!?

I Don't Need a Real Estate Agent!

Brie Bender, Broker in Charge | Beach Realty Group

In this age of technology, we have heard the sentiment “I don’t need a real estate agent to buy or sell a property. I can do it myself!” Now don’t tell anyone else this but in all reality, you don’t.

Companies, apps, and websites are making it easier and easier to go thru the home buying and selling process yourself. One thing you cannot automate, however, is human connection and emotions. Buying or selling a home can be a tremendously stressful process when you are not educated on how the process works. That’s where a real estate agent comes into play. At BRG we aren’t just agents, we’re REALTORS.

REALTORS® are different from other licensed agents because they are professional members of the National Association of REALTORS® and subscribe to its strict code of ethics. This is the REALTOR® difference for home buyers:

  • Ethical treatment. Every REALTOR® must adhere to a strict code of ethics, which is based on professionalism and protection of the public. As a REALTOR®’s client, you can expect honest and ethical treatment in all transaction-related matters. The first obligation is to you, the client.

  • An expert guide. Buying a home usually requires dozens of forms, reports, disclosures, and other technical documents. A knowledgeable expert will help you prepare the best deal, and avoid delays or costly mistakes. Also, there’s a lot of jargon involved, so you want to work with a professional who can speak the language.

  • Objective information and opinions. REALTORS® can provide local information on utilities, zoning, schools, and more. They also have objective information about each property. REALTORs® can use that data to help you determine if the property has what you need. By understanding both your needs and search area, they can also point out neighborhoods you don’t know much about but that might suit your needs better than you’d thought.

  • Expanded search power. Sometimes properties are available but not actively advertised. A REALTOR® can help you find opportunities not listed on home search sites and can help you avoid out-of-date listings that might be showing up as available online but are no longer on the market.

  • Negotiation knowledge. There are many factors up for discussion in a deal. A REALTOR® will look at every angle from your perspective, including crafting a purchase agreement that allows enough time for you to complete inspections and investigations of the property before you are bound to complete the purchase.

  • Up-to-date experience. Most people buy only a few homes in their lifetime, usually with quite a few years in between each purchase. Even if you’ve done it before, laws and regulations change. REALTORS® handle hundreds of transactions over the course of their career.

  • Your rock during emotional moments. A home is so much more than four walls and a roof. And for most people, property represents the biggest purchase they’ll ever make. Having a concerned, but objective, third party helps you stay focused on the issues most important to you.

Whether this is your first home purchase or sale, having an agent to turn to that has helped hundreds of clients thru this process is not an interaction that can be replaced by an app.

Source: Realtor Magazine, 7 Reasons to Work with a Realtor

Posted in BoydTeam Blog
April 24, 2019

Payment Options if You Owe the IRS

The IRS will work with you if you simply cannot pay in full

Tax Time

If you complete your tax return only to realize that you owe the IRS money, you can take some small comfort in knowing that you're not the first person to find himself in this predicament.

Yes, it can be particularly stressful if you've never owed the IRS before or if you just don't have the available cash to make a lump sum payment. The Internal Revenue Service has dealt with this dilemma many times before, however, so it offers some options and grace periods.

How Much Do You Owe? 

First, figure out how quickly you can pay off the tax debt. Paying the debt all at once will save you some money if you have the cash on hand or you can get it—the IRS will continue to assess late payment penalties up through the date you pay in full.

If that's not possible, however, the IRS will let you pay the debt over time. The downside to this is that interest and late charges will continue to accrue until it's paid off. 

If You Can Pay Within 45 Days 

If you can't pay your tax bill in its entirety right now but you know that you'll be able to do so within 45 days, send in a partial payment using the Form 1040-V payment voucher at the time you file your return. Most tax preparation software provides the form and it's also available online at the IRS website. 

Wait for the IRS to send you a letter detailing your outstanding balance and any late charges that have been added. The IRS usually provides a grace period for payment of between 30 to 45 days after sending that letter. Pay your remaining balance by the deadline set by the IRS.

If You Can Pay Between 45 Days and 120 Days 

The process is similar if you can pay within four months. Send in a partial payment using Form 1040-V and wait for the IRS to send you a letter telling you how much you owe including late charges. Then call the IRS at the number shown on the letter to request a short-term extension of time to pay beyond the date set in the letter.

Propose a definite deadline for paying off your balance in full and the IRS will note that date in its records. Use the payment voucher that's included with the letter to make your next and final payment.

Calling the IRS is important with this payment tactic because it will prevent the government from taking more aggressive collection actions. You're letting the IRS know that you're on top of the situation and you're trying to fix it.

If You Need More Than 120 Days

The IRS will usually let you set up a monthly payment plan, also called an installment agreement, if you're going to need a more significant amount of time to pay off your tax debt. This is a formal agreement to pay the IRS over time and the IRS will likely approve your payment plan as long as it will pay off your tax debt in three years or less.

Depending on how much you owe, you might also have to submit a financial statement. This is generally required if you owe more than $10,000 but streamlined installment agreement applications are available for taxpayers who owe up to $25,000.

The IRS does charge a fee to set up these plans. It ranges from $43 for low-income taxpayers up to $225 as of 2018. This is a one-time fee that's paid up front and it's typically included with your first payment.

You can apply for an installment agreement online at the IRS website if you owe $50,000 or less. 

Temporary Delay Collection

This option doesn't come with a set date by which you'll pay off the IRS and it's available only if the IRS agrees that collecting from you at this point in time would present an undue financial hardship to you.

Your tax debt doesn't go away. It's put on hold until such time as your finances recover. You must be able to prove that if you were to pay the debt, you would not be able to meet your necessary living expenses. The IRS will file your matter as "currently not collectible" but penalties and interest will continue to accrue.

The IRS is effectively agreeing not to aggressively pursue you for the money by way of levies and other collection avenues available to them.

When You Can't Pay Your Taxes at All

If you can't afford to pay your taxes at all, your best bet is to seek professional advice from a tax professional who's authorized to represent you before the IRS. This typically includes CPAs, attorneys, and enrolled agents.

Many tax clinics provide free or low-cost access to tax professionals and that's generally a good place to start if you need help. A competent tax professional can evaluate your options, such as requesting a temporary delay, setting up a partial payment plan, or negotiating a settlement through the offer in compromise program.


The IRS isn't really as heartless as its reputation would make it out to be. It also offers a Taxpayer Advocate Service for assistance in this and other unpleasant situations. The worst thing you can do if you owe the IRS money is nothing. It typically welcomes all overtures to get tax debts paid and it might even accept less than what you owe if your financial situation qualifies. 

Posted in BoydTeam Blog
April 23, 2019

The Worst States to Retire To

High Taxes Make These States Unfriendly For Retirees


Looking for a place to retire? You might steer clear of these states. Although each state on our list has plenty of positive selling points, other states may lend themselves better to retirees looking to relocate.

The map below shows a breakdown of the eight worst states for your retirement.

West Virginia

Although you’ll meet some incredible people in West Virginia, you won’t find the state scoring high on very many “best of” lists. Unfortunately, we have to agree when looking at the state from the lens of a retiree. Most retirement income, including Social Security, is taxed after the first $8,000, the average income for retiree households is only $40,000 and only 8 states scored below West Virginia in fiscal soundness. It also ranks near the bottom for retiree health. Only 57 percent of its population is able-bodied compared to the national average of 65 percent.

Alaska

If reality TV is any guide, America is fascinated with Alaska but not as a place to grow old. The harsh conditions and high cost of living—32 percent above the national average, might be why only 69,300 of its residents are over the age of 65.

Despite the collective “no” from seniors, there’s plenty of reasons why Alaska isn’t as bad as it sounds. No state income or sales tax, the annual dividend check from the state’s oil well savings ($1,100 per person) and, of course, the absolutely beautiful scenery.

Oregon

No sales tax, over 300 miles of beautiful coastline, Portland being the most bike-friendly city in the country, low crime rate, farmers markets everywhere and beautiful weather. What’s not to like about Oregon? The 9.9 percent top income tax rate for one. Also, the high cost of living that comes in 18 percent above the national average and the below average household income. At $53,799, that’s 16 percent lower than the average.

Minnesota

How does 44.3 inches of snow per year sound? Or an average low temperature of 0.2 degrees in January? Above average living expenses and below average income and the state taxes Social Security benefits as much as the federal government along with almost all other retirement income including military, government, and private pensions. Add to that the high state sales and income tax, and you can see why Minnesota might not be high on your list. On the other hand, it ranks sixth for the most agreeable state and the “land of 10,000 lakes” is a real thing.

Want waterfront property? No problem.

Kentucky

Unfortunately, Kentucky is either at the top or near the top of worst places to retire, including ours. The high rate of smoking, poverty and low physical activity along with a dismal rating for the quality of nursing home care place the healthcare situation at the bottom of the list.

On the other hand, the cost of living is low, median home prices are a mere $113,000, and the state doesn’t tax the first $41,000 of retirement income and doesn’t tax Social Security at all. And the state produces 95 percent of the country’s bourbon. That has to count for something.

Michigan

This poor state (literally) can’t get out of its own way. With cities like Detroit struggling to survive and the Flint, Michigan water crisis that made national headlines, the state hasn’t been cast in a positive light over the past handful of years. Add to that challenging winter weather, and an upcoming change where seniors will have to choose between having their Social Security taxed or $20,000 of their retirement income, and rising poverty, seniors are looking elsewhere.

Some bright spots—cost of living is 12 percent below the national average, and the scenery—yes!

Montana

You won’t have any trouble finding beautiful views in Montana but holding onto your money might be a challenge. The cost of living is 3 percent above the national average while income is 21 percent below. Montana will tax most of your retirement income including a top tax rate of 6.9 percent that isn’t just for the filthy rich. Once you earn $17,400 or above, 6.9 percent is your rate. Ouch!

By the numbers, Montana isn’t a place you want to move to for retirement but lifelong residents don’t often leave. Nearly 17 percent of the population is 65 or older and there’s always the snowbird option.

New Mexico


Most of the states on our list have been in the northern portions of the country but there are some steer-clear states in the southern portion as well. Leading that charge is New Mexico. The retiree poverty rate of 12 percent is the 3rd highest in the country. The tax on Social Security benefits and most other retirement income is probably a big reason for the high poverty rate although low-income seniors can receive an $8,000 exemption. On the bright site, healthcare costs are below average along with the cost of living.

Posted in BoydTeam Blog
April 22, 2019

How to Negotiate Lower Rates on Monthly Expenses

Close up teenage girl friends using cell phones

If you’re savings-savvy, negotiating is a great way to save on big-ticket items like a new car or home. But did you ever consider negotiating some of your smaller monthly expenses, too?

Contrary to common belief, you are not stuck with whatever rates your service providers offer you. Many recurring expenses, like phone service and even utilities, can be negotiated lower. And every extra dollar you can shave off your budget means one more dollar you can put towards something else—like paying off that credit card, building up your retirement funds or saving for that fantastic family vacation.

Consider these common budget categories you may be paying too much for—and how you can go about negotiating a better rate for yourself:

TV

Explore alternative options like free streaming TV and discounted subscriptions through services like Hulu, Netflix, and Roku. But if you still feel the need to pay for satellite or cable television service, there are ways to save.

Chances are you’ve noticed how often your current provider advertises great starter rates for new customers. You may have even gotten one yourself when you first signed up with them. But now that you’re a regular, longstanding customer, you find yourself paying hefty “standard” rates—and getting jealous of all the new customers who are getting a better bargain.

You don’t have to put up with it. Call the customer service line and let the company know that, as a loyal customer, you don’t like the fact that new customers are being treated way better than you are. You may not be able to get the special introductory rate you once had, but you could snag yourself some perks, like access to premium movie channels for 6 months or the ability to switch to a new package that wasn’t available when you first joined.

Phone

First and foremost: If you never use your landline, ditch it and go mobile-only. If you rely heavily on your landline and only need a cell phone for emergencies, consider a TracFone or pay-as-you service, so you only pay for what you need.

If, however, your cell phone is your lifeline and your extra appendage, there are still ways you can save. Take a long, hard look at your package terms and monthly usage to make sure you’re not paying for more minutes than you need. If you think you’re stuck with a pricey package just because the next level down doesn’t give you what you need, think again.

Some companies offer unadvertised packages that you won’t know about unless you ask. Call up and ask if there are any preferred customer rates or employer discounts you might qualify for.

If you’re out of contract, or your contract is due to expire soon, don’t renew! That one- or two-year contract might have snagged you a great deal on your phone, but if you don’t care about upgrading to the latest device, you can negotiate a lower monthly rate once you’re out of the contract because the provider knows they don’t have you hooked.​

Utilities

Don’t be fooled into thinking the big players in your area are your only options. More and more alternative energy providers are cropping up who might be able to offer you a more competitive rate. And even if your company has a monopoly in your area, there are still ways you cut your costs.

If you’ve recently installed energy-saving measures like upgraded windows and better insulation, your utility company might be willing to conduct an energy audit (or consider one from a third party) as leverage for negotiating a lower rate.

If you live in an area where temperatures fluctuate wildly from season to season, your heat provider may offer a budget billing option that spreads your heating costs across all months, meaning you’ll pay the same low, fixed amount each month (based on your past usage) rather than getting socked with huge bills in colder seasons. Monthly budget plans may also be available to you based on your current household income.

Credit Card Rates

Sick of seeing all the new low- or no-interest offers in your mail, while you continue to pay the same high rates on existing cards? (Or watch your APR climb even though your credit rating is good?)

You don’t have to deal with the hand the credit card companies have dealt you; many are more than willing to work with you to retain your business, as they know you’ve got plenty of other options out there.

If you’ve been making your payments regularly and/or paying more than the minimum, then you are a customer in good standing, and your company should be willing to fight to keep you.

Call up and let them know you’re thinking of transferring your balance to one of the many zero-interest cards that are currently courting you. Ask if there’s anything they can do to make it worth your while to stay with them. Most won’t let you walk without trying to offer you something—it’s up to your persistence how big their offer might be.

Negotiate the Right Way

Whatever you’re trying to negotiate, the key to success lies in keeping your tone polite, respectful and calm. As tempted as you may be to let them know how ridiculous you think your current fees are, companies will be much more willing to work with you if you say how much you’ve enjoyed their service and emphasize your history as a loyal customer.


Keep it positive, phrase it as a win-win, and most of all, give it a try! You never know what you can get unless you ask!


Posted in BoydTeam Blog
April 20, 2019

How To Switch to Cash Only for Your Budget

Woman taking cash out of wallet


If you are having a hard time sticking to your budget, you may find it beneficial to switch to cash for a few budget categories. It is important to carefully consider the things you will need to do in order to successfully switch a cash-only budget.

You may also be more likely to stick to your budget because of the psychological impact of using cash as opposed to a debit card to pay for something—you realize just how much it really costs. Here's how to make the switch.

Choose the Categories to Switch to Cash

The first step in switching to cash is to determine the budget categories that you are actually able to switch to cash-only. Some categories (such as a mortgage or student loan payment) may only be able to be made online.

But for those categories that you are able to use cash for, determine which you are consistently overspending on. This may be groceries or entertainment, eating out, or clothing. Everyone has their problem areas when it comes to spending. Once you know what yours are, you can switch them over to cash in order to curb your spending.

Stop Using Your Debit Card for These Categories

The next step is to stop using your debit card or checkbook to pay for anything in those categories, no matter what. Period.

If you are not able to do that, you may consider leaving your debit card at home for a few weeks and disconnecting any automatic payments you can access online, such as those through Paypal. This will help you break this bad financial habit.

Create a System to Separate Cash and Track Receipts

When using a cash-based budget, you need a way to track your cash purchases and also keep the different areas of your budget in which you'll be using cash separate.

A simple way to do this is to use the envelope system. You put the correct amount of cash into envelopes labeled with each budget category. You can only spend that amount on that area of your budget each month. You should also put your receipts into those envelopes so you can see where you spent the money at the end of the month.

Another strategy is to keep a running ledger as you spend the money.

Set Up a Time to Take Out the Cash

In order to be successful at a cash-only budget, you need to actually get the cash and separate it into categories. This may mean a trip to the bank or the ATM on payday, or another set day.

You can request that the teller gives you the money in the correct denominations, such as all $20s or $10s, so you can easily separate the money into the correct categories.

Plan Ahead When You Go Shopping

This type of budget requires that you learn to plan ahead. Generally, it’s not a good idea to carry huge amounts of cash around with you all of the time.

So you leave your grocery money at home unless you are going to the grocery store, and take only $20 to work if you plan on eating out that day. You get the idea. Bonus: This will also help to cut back on your impulse purchases.

Stick to Your Limits

As with any budget, this requires self-discipline to not spend all the money in one category. This also means that you do not use your debit card or your credit card to cover shortfalls.

However, you can switch money between envelopes if you find that you have overspent on your grocery budget, but you are out of food halfway through the month. But this means that you will have to cut spending in other areas.

Adjust Your Categories 

You should adjust your budget once you have followed it for a few months. You may find that you don’t have enough budgeted for groceries, but you always have money left over in the gas category, or you that you may need to sacrifice some of your entertainment money so that you can eat all month.

Other Tips:

  1. Using cash may not always seem very convenient, but it is a great way to stop yourself from overspending. It makes you think about your purchases, and consciously consider how much you are spending. This type of budget can also help you to stop using your credit cards, as well. If you need to make online purchases, you may want to use Google Wallet to separate the categories from your regular checking account.
  2. Consider using an expanding pocket file that fits into a purse to put your cash in, but separated according to budget category. However, this does mean carrying all of your cash, so it might not be the best option if that makes you nervous. Consider carrying all your cash for the week instead of all the cash for the month instead.


  1. If you are married, budgeting as a couple can be very difficult. A cash budget can help make budgeting easier. You can divide the money between your individual categories, and leave the grocery money or entertainment money where you can both access it if you need it.
Posted in BoydTeam Blog
April 18, 2019

Save Money or Pay Off Debt

Should You Save Money or Pay Off Debt?


Paying debt and saving money are both very important financial goals. They’re also steps you have to take to reach a bigger life goal—living well during retirement. You may want to go into retirement debt-free, but focusing on debt repayment now could mean you have to sacrifice building up your retirement savings. But how do you choose the best place to spend your money?

You might need to adopt a blended approach and save some while you pay down some of your debt at the same time. When you understand the pros and cons of paying only debt or only savings, you can better assess your own situation and see how to tweak your savings and debt-payments to move your goals forward in each area.

Paying Debt and Skipping Savings

If you pay your debt first and put no money in savings, the downside is that you'll have nothing but your credit cards to fall back on if you have a financial emergency. You can count on some type of expense coming, and it's usually when you least expect it. Using your credit cards to fund an emergency only makes it harder to pay off your debt.

When to Put Debt Payment First

Pay your debt down before saving if you have credit cards with high interest rates. By reducing your owed balance, you'll also reduce the dollar amount of interest you pay each month. This can give you a bigger break financially than gains you could be earning in the stock market, and certainly more than you'll earn in a savings account.

When it comes to fixed-payment loans, such as a student loan or mortgage, extra payments can reduce the duration of your loan because your lender will apply the money to future payments. However, be aware that the lender won't recalculate the loan to lower your monthly payments. If you're worried you'll lose a tax deduction by paying off either of these types of loans early, the tax deduction is likely smaller than the amount of interest you would have paid for the year on your loan.

Saving Without Paying Down Debt

If you save first and don’t focus on paying down your debt, you will pay more money over time in credit card interest charges. Since credit card interest rates are often higher than savings interest rates, you end up spending more money on debt interest than you'd earn on your savings investment.

The other problem with saving first is that you risk entering retirement with debt. You may find that you can’t live comfortably on your retirement savings and keep paying your debt. So you’d have to either live on a strict budget to pay off your debt or go back to work until you can pay off your credit cards.

When to Save First

While it might feel uncomfortable, there are actually some situations where it makes sense to pay into your savings first and then work on your debt. If you're lucky enough to have debt with a low interest rate, it makes better sense to put most of your extra money into savings first, at least until you've filled up your emergency financial fund. Shoot for funds to cover thee to six months of expenses.

If this seems difficult in the short term, focus on building a small $1,000 emergency fund. That money can cover many small but urgent expenses like car repairs that would otherwise be charged to your credit card. Once you jumpstart your emergency fund, then you can put the focus back on paying off your debt.

If you delay your retirement savings until your debt's gone, it will have negative consequences. The longer you wait to start saving, the more you have to pay to reach your retirement goal.

If you start saving earlier, you get the benefit of years and years of compound interest on your investment. For example, say that Bill, a 28-year old, starts investing $5,000 per year and continues until he retires at 58. He will have saved $150,000 with 30 years of compounded interest, which will bring his total retirement savings to about $540,700.

His friend Larry started putting away $5,000 each year when he turned 18, until he also retired at 58, with $200,000 invested with 40 years of compounding. Those 10 extra years of compound interest grew Larry's total savings to a whopping $1,142,800, or more than twice the amount of his friend Bill's nest egg.

To increase your retirement savings, take advantage of your employer’s offer to match contributions to your 401(k) plan if offered—don’t turn down this free money. There are also tax benefits that come with retirement savings. The money you contribute to a 401(k) can often be excluded from your taxable income, resulting in a smaller tax burden. Even if you put money into a 401(k), you may be able to budget your spending and find money to allocate to paying off your debt.

The Best Approach Is to Pay Both


Ultimately, it's best to find a balance between the amount you spend on debt and savings each month. It isn’t wise to put off either of these in lieu of the other, so devise a way that you can split your money between the two. For example, if you have an extra $1,000 each month, put $500 toward your debt and $500 toward saving. You might pay a bit more in interest, but you'll have the peace of mind that comes with having money in the bank to keep you out of the debt cycle and make your retirement years more pleasant.


Piggy bank illustration

Posted in BoydTeam Blog
April 17, 2019

The Jewelry in Your Kitchen Design

The Jewelry in Your Kitchen Design
 

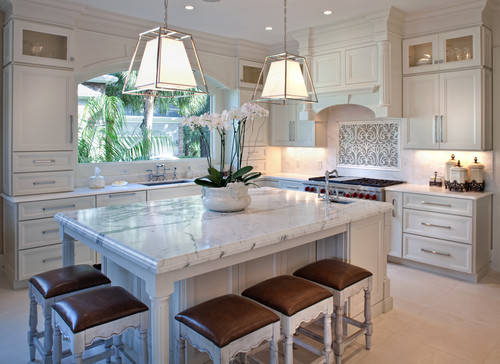
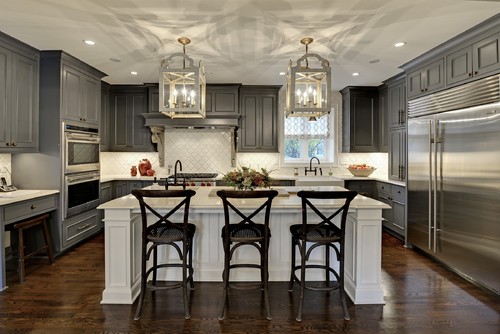
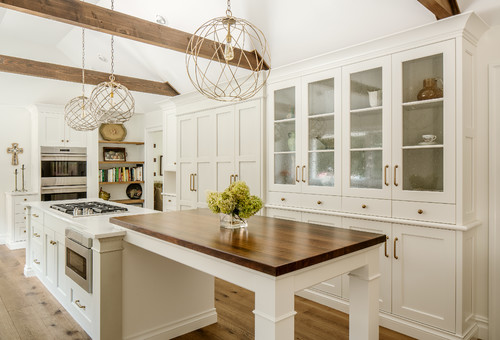
Great lighting is definitely stealing more of the spotlight in kitchen design lately. Pendant lights that hang from the ceiling above your kitchen island—usually in a row of two or three–is really a place to show off lighting to dress up your kitchen.

Some designers refer to pendant lights as the jewelry of your kitchen. They add a little decorative sparkle to catch the eye.

Blown glass pendants are one of the top trends. This is a clear glass light fixture with an exposed Edison light bulb inside. Glass pendants in geometric shapes, like a glass boxed pendant or a glass sphere, are popping up in more kitchens lately.

Glass pendants can be a great choice for smaller kitchens or kitchens within an open floor plan. That’s because the see-through glass doesn’t disrupt the line of sight in your kitchen space. The lighting adds just enough statement and shine to accent that kitchen island.

Check out a few examples.

Posted in BoydTeam Blog