CATCH THE WAVE

Myrtle Beach Real Estate

We Specialize in Myrtle Beach, SC Real Estate. Lots of options are waiting for you in Myrtle Beach, South Carolina and choosing the right realtors can help you in finding the perfect area and the right home for you and your family and make your dream a reality!  Let us help you in making one of the biggest, if not the biggest, decisions in your life.   

We were both born and raised along the Grand Strand and know the entire Horry County, so no matter what style of home you are looking for or what area you prefer, we can help you!  Please give us a call and let us help you make your dream a reality!  843-222-8566.

Eddie & Julie Boyd - The Boyd Team - Realtors

Myrtle Beach Real Estate - INNOVATE Real Estate


Aug. 14, 2018

First-Time Home Buyers Continue to Put Down Less Than 6%!

First-Time Home Buyers Continue to Put Down Less Than 6%! | Simplifying The Market

First-Time Home Buyers Continue to Put Down Less Than 6%!

According to the Realtors Confidence Index from the National Association of Realtors, 61% of first-time homebuyers purchased their homes with down payments below 6% in 2017.

Many potential homebuyers believe that a 20% down payment is necessary to buy a home and have disqualified themselves without even trying, but in March, 71% of first-time buyers and 54% of all buyers put less than 20% down.

Ralph McLaughlin, Chief Economist and Founder of Veritas Urbis Economics, recently shed light on why buyer demand has remained strong,

“The fact that we now have four consecutive quarters where owner households increased while renters households fell is a strong sign households are making the switch from renting to buying.

Households under 35 – which represent the largest potential pool of new homeowners in the U.S. – have shown some of the largest gains. While they only make up a third of all homebuyers, the steady uptick in their homeownership rate over the past year suggests their enormous purchasing power may be finally coming to [the] housing market.”

It’s no surprise that with rents rising, more and more first-time buyers are taking advantage of low-down-payment mortgage options to secure their monthly housing costs and finally attain their dream homes.

Bottom Line

If you are one of the many first-time buyers unsure of whether or not they would qualify for a low-down payment mortgage, let’s get together and set you on your path to homeownership!

Posted in BoydTeam Blog
Aug. 14, 2018

Have You Outgrown Your Starter Home?

Have You Outgrown Your Starter Home? | Simplifying The Market

Have You Outgrown Your Starter Home?

For many Americans, buying their first home is their first taste of achieving part of the American Dream. There is a sense of pride that comes along with owning your own home and building your family’s wealth through your monthly mortgage payment.

It may seem hard to imagine that the first home you purchased (which made your dreams come true) might not be the home that will allow you to achieve the rest of your dreams. The good news is that it’s ok to admit that your home no longer fits your needs!

According to CoreLogic’s latest Home Price Index, prices in the starter home market have appreciated faster than any other category over the last year, at 9.4%. At the same time, inventory in this category has dropped 14.2%.

Have You Outgrown Your Starter Home? | Simplifying The Market

These two stats are directly related to one another. As inventory has decreased and demand has increased, prices have been driven up.

This is great news if you own a starter home and are looking to move up to a larger home as the equity in your home has risen as prices have gone up. Even better is the fact that there is a large pool of buyers out there searching for your starter home to help them achieve their American Dream!

Bottom Line

If you have outgrown your starter home, contact a local real estate professional who can explain the market conditions in your area and help you find your next home!


Posted in BoydTeam Blog
May 23, 2018

10 Money Mistakes To Avoid This Year

,  Opinions expressed by Forbes Contributors are their own.

Shutterstock

There’s a lot of talk about what to do right with your money.

Now, let’s talk about what some do wrong with their money, and what you can do to avoid their mistakes.

Here are 10 money mistakes that you should avoid this year:

  1. Skipping a payment

You got busy. You forgot. The balance was just too high. So, you skipped making the payment when it was due.

No.

Don’t skip a payment. Whether it’s a student loan, personal loan, credit card, auto loan or mortgage, you have a contractual commitment to repay your debt. Of course, you can skip whatever payments you want, but you’ll be assessed fees and penalties. Plus, missed payments can hurt your credit score.

  1. Making a late payment

While not as bad as outright skipping a payment, a late payment also can hurt your credit score. Each month, your goal should be to make on-time payments in full. To avoid late or missed payments, enroll in auto pay. It will save time and headaches.

  1. Not creating an emergency fund

Too many think disaster will never strike, or it only happens to certain people.

Survey says? Look, things will go wrong. It will happen before you realize it happens. An emergency fund is the safety net that you need in place before disaster strikes. Consider it a financial first aid kit.

At a minimum, you should save 6-9 months (preferably longer) of cash in a separate bank account to cover necessary expenses in case you unexpectedly lose your job, get sick or have another unforeseen expense. Don’t postpone or go without an emergency fund -  you need one.

  1. Borrowing debt you can’t pay back

Gaining access to credit often is easier than you think. However, if you can’t pay back that debt in full or afford the monthly payments, then don’t borrow the debt. It sounds simple, but too many ignore this basic principle. Do your homework. Understand your interest rate and monthly payment.

The last thing you want is to borrow debt you can’t repay - and then you’re stuck with a big bill.

  1. Buying more house than you can afford

Buying a house can be a smart move for you and your family. It can help build a foundation and bring stability to your life.

When you find your dream home, it’s also easy to borrow more than you can afford. Separate the beauty from cost of the house - they are two different things. One is for you to enjoy; the other you need to pay for.

  1. Not refinancing student loans

Student loan refinancing enables you to combine your existing federal and private student loans into a new, single student loan with a lower interest rate. The result can be a lower monthly payment with a single payment, due date and student loan servicer.

To get approved, you will need strong credit (preferably 680 or higher) and strong income, but the savings can be significant. Lenders also may evaluate your monthly cash flow and debt-to-income ratio, including other factors. You can apply to multiple lenders at once, and even check your new rate before your credit is checked. Approval is not guaranteed, but it’s worth the try to how much you could save.

This free student loan refinancing calculator can show you how much you can save.

  1. Not consolidating credit card debt with a personal loan

Credit cards can be great financial tools. If you have credit card debt, however, you could be paying 10-20% interest.

One option is to consolidate your credit card debt with a personal loan. A personal loan is unsecured credit that is typically repaid within 3-7 years. If you can obtain a lower interest rate with a personal loan compared to your credit card interest rate, you could save interest costs.

You can use this free personal loan calculator to determine how much you could save on your monthly payments.

  1. Borrowing against your retirement account

Your retirement account is there for a simple reason: to help cover your expenses in retirement.

If you make an early withdrawal, you could face a penalty  as well as taxes. Likewise, taking a loan against your retirement account also is a risky proposition, even with a relatively low interest rate. There’s always a chance you can’t pay back the loan, or won’t be able to “replenish” your retirement savings.

  1. Not using financial calculators

When you make a financial decision, it’s helpful to quantify that decision. A financial calculator can help make a complex decision simpler. Why? Financial calculators provide transparency, and they are essential tools to help you make better decisions.

  1. Not comparison shopping for financial products

When you buy a financial product – a student loan, credit card, personal loan, auto loan or any other product – you want to comparison shop. Understand the differences among your choices. Determine the best rates and the best terms for your specific situation.

If you can avoid these 10 mistakes, you’re in better shape than most. Feels good to be ahead of the pack, right?

Zack Friedman is a keynote speaker and Founder & CEO of Make Lemonade, a personal finance comparison site that helps you live a better financial life.


  •  
  •  
  •  
  •  
  •  
Posted in BoydTeam Blog
April 23, 2018

5 Budgeting Tips For Homebuying


5 Budgeting Tips For Homebuying

By Jessica Thiefels

Buying a home will likely be one of the biggest financial transactions you make, and preparing your budget beforehand makes the home buying process much less stressful. The following tips and expert insight can help you get your budget in order before you make the big transaction.

1. Organize Your Finances

You may know how much you have in your checking and savings accounts, but do you know how much you spend on household expenses each month? Or how much high-interest and credit card debt you have? It's important to get a clear idea of where your money goes in order to figure out what you can afford and what your home buying timeline looks like. Personal finance experts at OnStridesuggest breaking down your finances into the following categories:

  • Level 1: Basic Budgeting: Basic financial needs, like rent, groceries and gas.
  • Level 2: Emergency Funds: In case of an accident or other costly event.
  • Level 3: Passive Preparation: 401K or IRA plans that you manage yourself.
  • Level 4: High-Interest Debts: Anything with an interest rate of 10 percent or more.
  • Level 5: Long-Term Savings: Money you've already put away for your home, or have been saving otherwise. (Note this is different than your emergency fund – if you don't have a savings outside of your emergency fund, separate them now.)
  • Level 6: The Leftovers: Is there still money floating around in your account? Determine how you'll best use this to prepare for home buying – play the market, put it in a high-yield savings account, etc.

With your finances categorized and organized, you can start to set goals for how much you need to save, and for how long, in addition to where you need to cut back.

2. Do the Math

Before you set any home-buying goals, do the math to figure out how much you can afford. This will also dictate how much you need to save. Dave Ramsey shares five steps to figure this out:

  • Add up your income
  • List household expenses (If you organized your finances above, then this step is already done!)
  • Calculate home ownership costs (Check out this list from US News)
  • Give your budget room to grow: "Life is going to happen in the years you occupy your home. Before you get married to a mortgage, look ahead and consider events that might increase your living expenses down the road."
  • Make adjustments: Cut back here, save more here, etc. (See the next section)

3. Set Goals

While the overarching goal is to buy a home, setting smaller goals will help you stay on track and feel successful while you make your way there.

As you set goals, remember that you don't need to be solely focused on saving. You may want to set goals for cutting back on spending as well. Here are a few to consider:

  • Save $1,000 in 3 months
  • Switch to a cheaper gym
  • Cancel my cable bill by the summer
  • Go out to eat just once each week
  • Buy one less coffee weekly this month

4. Write Your Budget

The math has been done, goals have been set and now it's time to write your monthly budget, which should take into account:

  • Total to be saved each month
  • Life expenses
  • Any unusual expenses for the month

In the end, you'll have a total spend for life expenses and a total amount to be saved by month's end. You can use a spreadsheet and do this by hand, or download one of these budgeting apps.

5. Update Weekly; Reassess Regularly

The final step is holding yourself accountable to your goals and regular updates of the budget. If you make a purchase that wasn't planned for, add it to your budget and readjust how much you'll be able to save that month.

Remember that a budget is fluid, and there are many "life things" that will come up and throw it off. That's okay, as long as you stay focused on the goals you've set for yourself. If you go over budget one week, reel it in the following so you can stay on track for the month.

As a homeowner, there are dozens of expensive problems that could arise. Get into a habit of budgeting now so you're prepared for these financial challenges when they inevitably pop up.

Posted in BoydTeam Blog
April 9, 2018

Paw-sitive Reinforcement: 5 Ways to Help Pets Adjust After a Move

Paw-sitive Reinforcement: 5 Ways to Help Pets Adjust After a Move


Moving can be stressful for every family member – including the four-legged ones. Every animal reacts differently to new living quarters, and temperament has a lot to do with it. Some pets take a move in stride, while others exhibit anxiety or insecurity for days or weeks.

Here are 5 things to consider as the big move approaches and after you're in your new home.

1. A little help from the vet
Ask your veterinarian for recommendations on easing the transition. If your pet is generally anxious or high-strung, it might be worth asking your vet whether a mild calming medication might help during the transition period. It's also not uncommon for vets to prescribe gentle stress relief for during travel.

2. Time to explore
Upon moving in, give your pet time to explore the house gradually, rather than letting it loose to roam at will. Limit it to one area – perhaps the kitchen – for a few hours until it calms down. Show the pet where you've placed its familiar items like the food dish, water bowl and bed. You might want to keep a dog on a leash for an initial home tour. If you have a yard, avoid letting pets out unsupervised for several days until you're sure they can't climb or dig out from under the fence.

3. A walk in the park
Help release anxiety and pent-up energy by take your dog for a walk and sniff through the neighborhood. While people learn about a new place primarily by visual cues, dogs depend on their noses.

4. Helping the feline in your life
Territorial by nature, cats often experience more issues with moving than their canine counterparts. Keep your cat safe in its carrier upon arrival, placing it in a quiet area. When the hubbub dies down, let it out in an enclosed room away from main traffic areas. Provide your cat with familiar objects, such as a bed, litter box and toys. Encourage it to explore the room, perhaps by strategically placing cat treats.

5. Update pet IDs
Amid the hustle and bustle of the move itself, don't forget to update your pet's identification information before you move. This way, if Fluffy or Fido slip out the door, anyone who finds them can easily return them to their new home. Also, some municipalities require licensing within a certain time frame of moving. If your pets are microchipped, contact the registration company and give them the new information.

Looking for a place that's perfect for you AND your pets? RE/MAX can help guide you there.

Posted in BoydTeam Blog
April 8, 2018

Closing the gap on the real estate closing process

closing the gap on the real estate closing process

Time for a tech upgrade?

April 6, 2018


Today, homebuyers can tour homes, see the neighborhood, and research the history of a property all from the comfort of their couch. Technology has streamlined the front end of the purchase process, but the actual closing remains largely stuck in the past.  Research from the National Association of Realtors shows that nearly 40% of home buyers rank understanding the closing process and the related paperwork as the top challenge.  Tech savvy consumers who have looked at homes and even virtually furnished them with a smartphone are confronted with a mass of old-school paperwork and disconnected procedures when it is time to buy.

15 Degrees of Separation

In a typical real estate transaction, there are approximately 15 different players, including an appraiser, a title examiner, a home inspector, a buyer, a seller, buyer’s and seller’s agents, a lender (which includes the loan officer, processor, and underwriter), a seller’s attorney, and a closing attorney (including paralegals). With such a large line-up, it can be hard for buyers and sellers to keep the roles straight let alone understand all of the intricacies of the close. Further, the communication between these various parties typically took place at best via email and sometimes still through fax! To an ever-connected society, this can feel like a painful experiment in time travel.

In an industry that is designed to help consumers participate in the American dream, the closing process is a nightmare.

Painful, Intense, Taxing and Inefficient

As a long-time closing attorney in Massachusetts, we suffered the same pains as many in the industry. Consumers were confused and we were buried in tedious inefficient closing functions performed on multiple platforms. For example, we ordered a title abstract by email and then received the abstract from the examiner by PDF attachment or written report in the mail which had to be scanned into our server.

We had to draft a separate form to order a tax certificate from the municipality.  We used real estate software to draft the title commitment, then used the title company’s system to obtain a required Closing Protection Letter (“CPL”). 

An intern or junior admin copied the property’s existing legal description by typing up a new Word document.  To obtain seller documents and schedule the closing, we emailed the seller’s attorney or paralegal and attachments were sent to us by email.  Any personal and private information (e.g., borrower authorizations for mortgage payoffs) would have to be faxed.  We separately emailed buyers to confirm spelling of their names, schedule closings, and deliver documents.  Additionally, we emailed realtors to obtain their commissions, receive transactional forms (e.g., condominium documents and financials) and schedule closings.

The Software Setback

Software programs did little to solve the root problem. As the escrow agent, we used separate software to manage all funds.  Each vendor and fee had to be entered into our real estate software or in the lender’s software platform to generate a Settlement Statement.  Separately, each payee was entered into the ledger utilizing a different funding software.  To denote the recording information, we transcribed the Book and Page by hand into our file, and manually entered it in our real estate software.  Electronic recordings were done by separate software.  When funding, we would track letters and packages through the FedEx website.  If it all sounds slow and painful, it was.

That’s how we used to do it and from my conversations with others, that’s still how many in our industry continue to operate. Given those inefficiencies we sought out technology that would both streamline our process as well as provide us comfort that our processes would continue to be compliant with the litany of security and privacy rules we are required to follow.

Evicting Inefficiency

Today, we coordinate our closings on a single platform.  We conducted our due diligence on a variety of technology solutions, most of them solved a single task. Ultimately, we decided to use Qualia to provide us with a unified, collaborative, and compliant system.  With Qualia, the closing is a much more coordinated process. The title examiner drops the title abstract into our platform.  The tax certificate, CPL and title commitment letters are all generated internally from the platform.  The existing legal description is scanned and copied in our platform.  We are able to automatically send out requests to buyers for contact information and to realtors for commission statements from the platform. We have a shared calendar to schedule and memorialize closings with all parties right in Qualia.  These are huge time-savers. 

In order to comply with numerous state and federal laws, our office is required to safeguard our client’s nonpublic personal information.  We are now able to utilize a “Connect” feature that allows all parties to upload documents and email on a secure platform.  This is especially helpful when cybercrimes and unauthorized access to computer systems are on the rise. 

Additionally, my entire staff can view a memorialized record of all transaction correspondence.  I can enter a note on a file that all members of my team can view.  We can share condominium documents, deeds, and settlement statements with the intended parties.  Seller’s attorneys can securely upload their clients’ payoff information and wiring instructions. Further, we have our funding software built into the platform, which also is a major benefit.  All deed and mortgage recordings are synced into our system, and all letters and closing packages sent by registered mail service are automatically entered in the platform.

It’s Time to Unify the Closing Process

My firm’s operational change highlighted that our industry, which relies on precedent, was reluctant to change. We believe these roadblocks can be overcome to improve our daily practices as well as our clients’ experiences with us. Collaborative software allows all parties in a real estate transaction to work toward the same goal expediently and efficiently.

 

Posted in BoydTeam Blog
April 3, 2018

NOT Owning Your Home Can Cost You a Lot of Money!

NOT Owning Your Home Can Cost You a Lot of Money!

NOT Owning Your Home Can Cost You a Lot of Money! | MyKCM

Owning a home has great financial benefits, yet many continue to rent! Today, let’s look at the financial reasons why owning a home of your own has been a part of the American Dream for as long as America has existed.

Realtor.com recently reported that:

“Buying remains the more attractive option in the long term – that remains the American dream, and it’s true in many markets where renting has become really the shortsighted option… as people get more savings in their pockets, buying becomes the better option.”

What proof exists that owning is financially better than renting?

1. In a previous blog we highlighted the top 5 financial benefits of homeownership:

  • Homeownership is a form of forced savings.
  • Homeownership provides tax savings.
  • Homeownership allows you to lock in your monthly housing cost.
  • Buying a home is cheaper than renting.
  • No other investment lets you live inside of it.

2. Studies have shown that a homeowner’s net worth is 44x greater than that of a renter.

3. Just a few months ago, we explained that a family that purchased an average-priced home at the beginning of 2018 could build more than $44,000 in family wealth over the next five years.

4. Some argue that renting eliminates the cost of taxes and home repairs, but every potential renter must realize that all the expenses the landlord incurs are already baked into the rent payment– along with a profit margin!!

Bottom Line

Owning a home has always been, and will always be, better from a financial standpoint than renting.


Posted in BoydTeam Blog
March 30, 2018

The Cost of Renting vs. Buying Today

The Cost of Renting vs. Buying Today [INFOGRAPHIC] | Simplifying The Market

Posted in BoydTeam Blog
March 29, 2018

99% of Experts Agree: Home Prices Will Increase

99% of Experts Agree: Home Prices Will Increase


Some believe that the combined effects of the new tax code and rising mortgage rates will have an adverse impact on residential real estate prices in 2018. However, the clear majority of recently surveyed housing experts believe that home values will continue to rise this year.

What is the Home Price Expectation Survey?

Each quarter, Pulsenomics surveys a nationwide panel of economists, real estate experts and investment & market strategists. Those surveyed include experts such as:

  • Daniel Bachman, Senior Manager, U.S. Economics at Deloitte Services, LP
  • Kathy Bostjancic, Head of U.S. Macro Investors Service at Oxford Economics
  • David Downs, Real Estate Finance Professor at VCU
  • Edward Pinto, Resident Fellow at American Enterprise Institute
  • Albert Saiz, Director at MIT Center for Real Estate

Where do these experts see home values headed in 2018?

Here is a breakdown of where they see home values twelve months from now:

  • 21.6% believe prices will appreciate by 6% or more
  • 71.6% believe prices will appreciate between 3 and 5.99%
  • 5.7% believe prices will appreciate between 0 and 2.99%
  • Only 1.1% believe prices will depreciate

Bottom Line

Almost ninety-nine percent of the top experts studying residential real estate believe that prices will appreciate this year, and over 93% believe home values will appreciate by at least 3%.

Posted in BoydTeam Blog
March 26, 2018

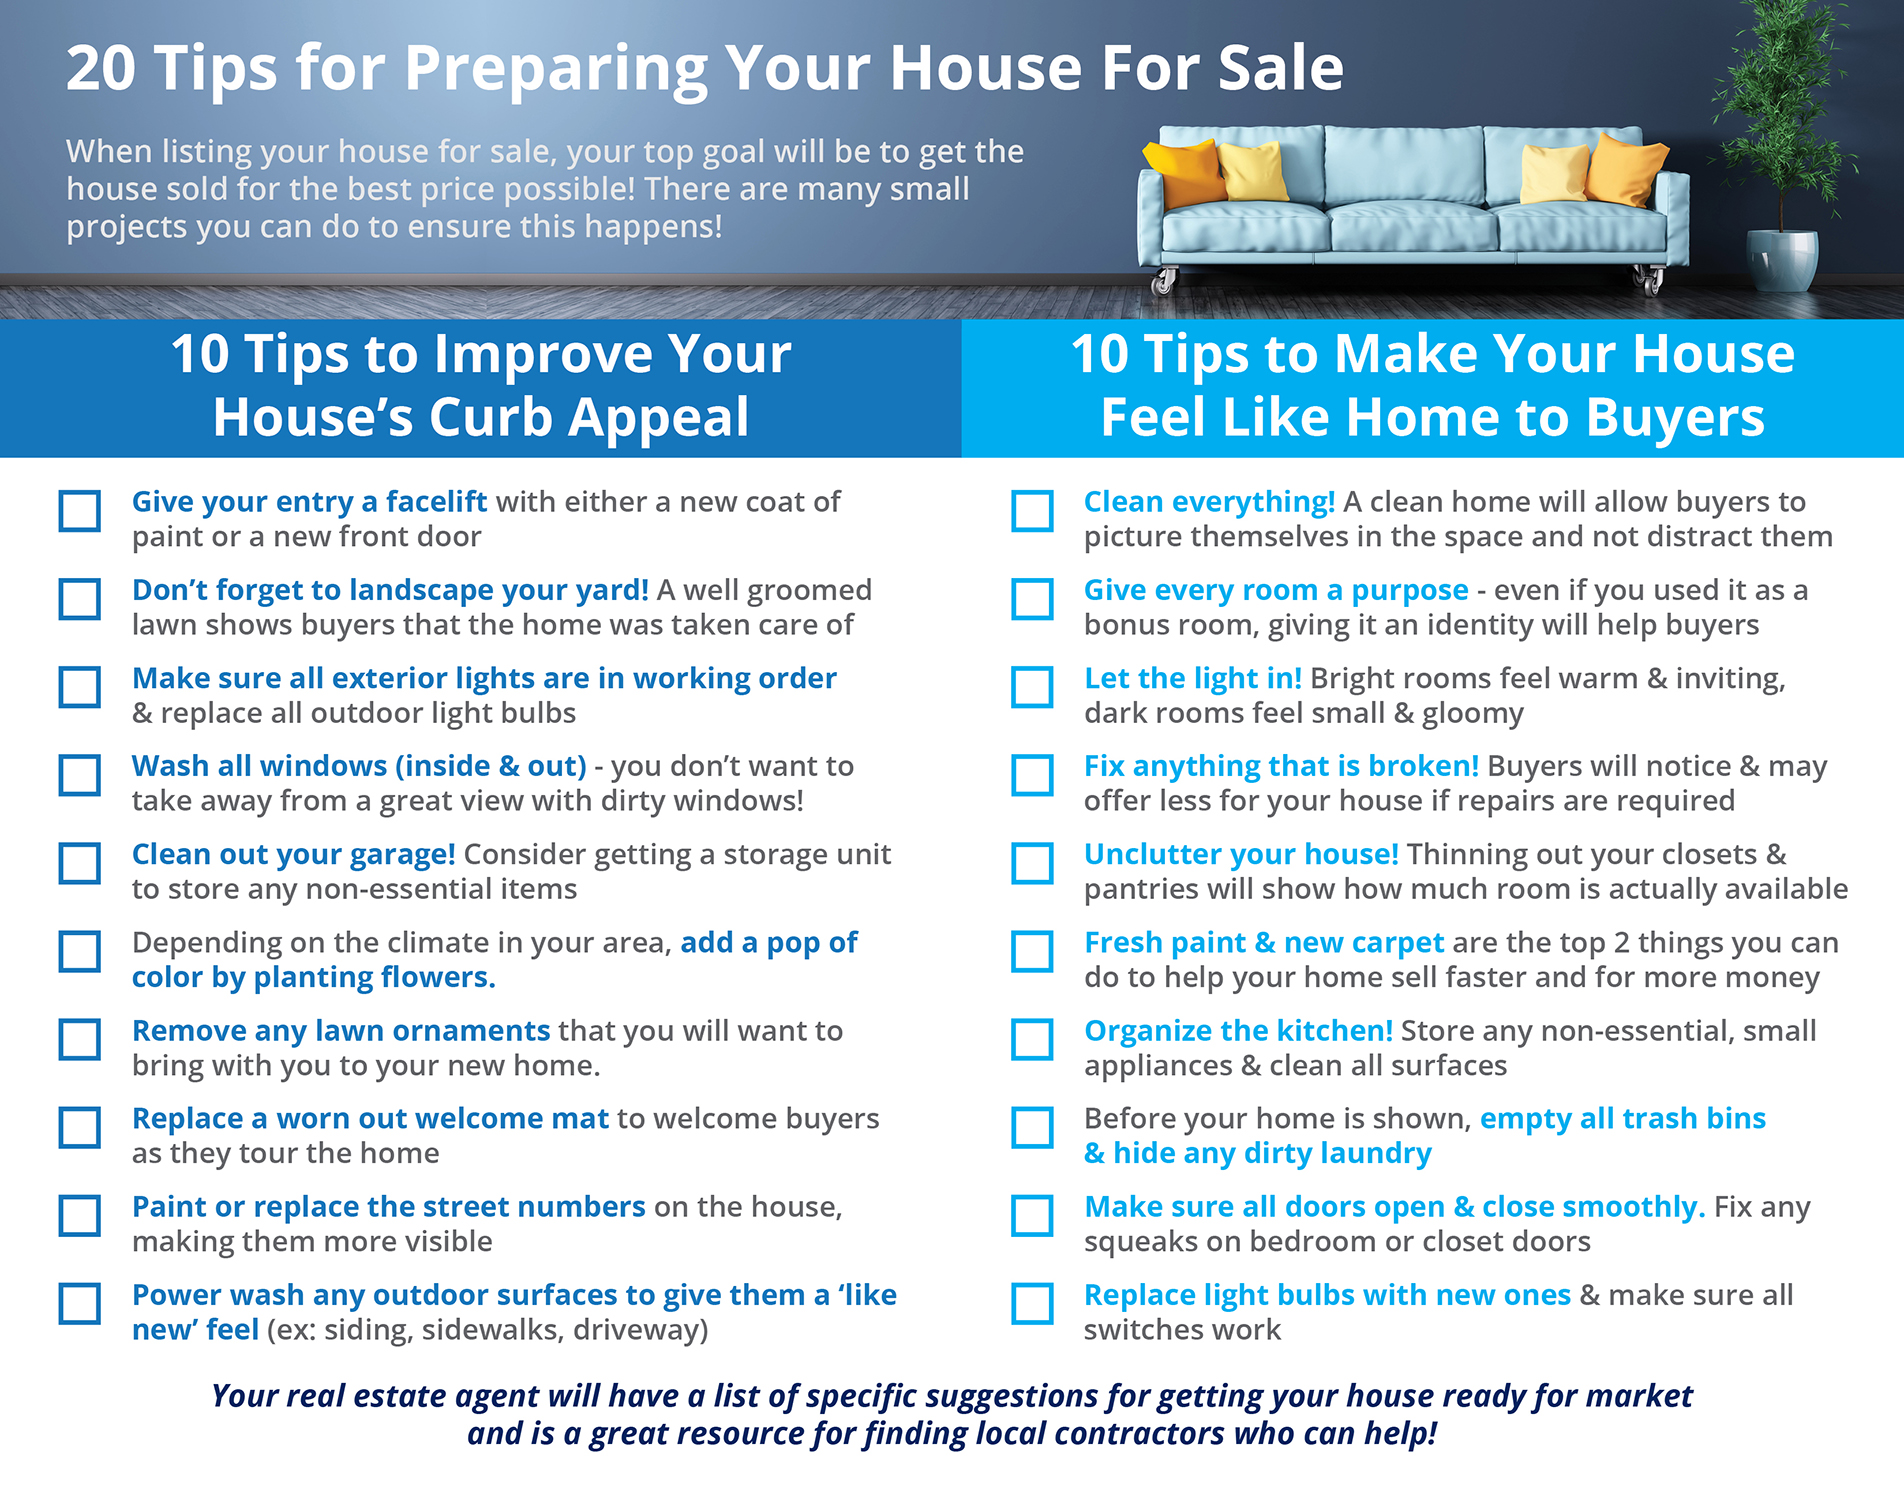
20 Tips For Preparing Your House For Sale

Posted in BoydTeam Blog